U.S. SSD Offset: Check the 80% Rule Before a Workers’ Comp Settlement

Yes, the SSA can reduce your SSDI so that your combined SSDI and workers’ comp payments stay at or under 80% of your average current earnings. The SSA POMS rules on lump-sum proration decide how long that reduction lasts. Lump sums are spread over time, and the offset generally runs only while that prorated period or your periodic payments last, or until full retirement age.
TL;DR:
- The SSA uses the highest of three ACE calculations, so ask which earnings method it applied and request the figures if your offset seems excessive.
- When an award omits a proration method, the SSA considers all three and uses the most favorable; itemized, genuine expenses can also shorten the period.
- Recognized reverse offset applies in 17 states and Puerto Rico; there, the state reduces workers’ compensation, so verify recognition before building a settlement estimate.
- Report payment changes and settlements to the SSA in writing; restoration after workers’ compensation ends may not happen automatically, so keep proof of delivery.
Table of Contents
- How does the 80% offset rule work?
- How does the SSA calculate your average current earnings?
- How are lump-sum settlements prorated?
- Which states use reverse offset?
- What should your settlement say before you sign?
- Who qualifies for SSDI and workers’ comp, and why does it matter for offsets?
- How do you claim SSDI alongside workers’ comp?
- What challenges come up with SSDI offsets, and how do you handle them?
- How do partial disability and vocational rehabilitation affect the offset?
- What happens when your workers’ comp benefits increase?
- How does the 80% rule play out in real scenarios?
- Why we built a 50-state calculator for this problem
- How can you estimate offsets and settlements with our calculator?
- FAQ
- Sources
How does the 80% offset rule work?
The rule comes from the Social Security Act, and it targets a specific overlap. If you collect both SSDI and workers’ compensation, your combined monthly benefits cannot exceed 80% of your average current earnings (ACE) from before you became disabled. When they do, the SSA lowers your monthly SSDI check by the excess.
Under SSA policy, combined SSDI and workers’ comp cannot exceed 80% of your ACE, and any excess comes out of your SSDI payment.
That is the headline, but two details change the math in your favor. And the offset can never push your combined benefits below your original SSDI amount.
Several events end or pause the reduction:
- Your periodic workers’ comp payments stop.
- The proration period for a lump-sum settlement runs out.
- Your state has a reverse-offset law that the SSA recognizes, so the state reduces your workers’ comp instead.
- You reach full retirement age (FRA).
Because offsets can last for years, it pays to know which of these endpoints applies to you before you sign anything or accept a payment schedule.
How does the SSA calculate your average current earnings?
ACE sets the ceiling, so the way the SSA calculates it decides whether an offset happens at all. The SSA tests three methods and uses whichever produces the highest figure, because a higher ACE raises the 80% threshold. Those methods, described in POMS DI 52150.010, are:
- High-1: your single highest year of covered earnings.
- High-5: the average of your best five consecutive years.
- Average monthly wage (AMW): your average monthly wage over the relevant earnings record.
Here is a quick illustration. Say your best single year of unindexed earnings was $60,000, which works out to $5,000 a month. Your ACE under High-1 would be $5,000, and 80% of that is $4,000. If your SSDI is $2,000 and your workers’ comp is $2,500, you are at $4,500 combined, so the SSA would reduce your SSDI by $500 to land at the $4,000 ceiling. If instead your High-5 or AMW came out higher, the ceiling would rise and the offset would shrink or disappear. All figures in this example are illustrative, not market data.
The SSA computes ACE from unindexed earnings, which surprises many people who expect inflation adjustments. Its systems calculate ACE automatically in most cases, though years above the maximum taxable amount may need a manual check.
Pro Tip: Ask the SSA which of the three methods it used and request the earnings figures behind it. A wrong ACE is one of the most common reasons an offset is larger than it should be.
How are lump-sum settlements prorated?
A lump-sum settlement does not escape the offset. The SSA treats it as a substitute for periodic payments, which means it is spread out, or prorated, over a period of time. Lump sums are subject to the same offset provisions as weekly checks, and the SSA uses the prorated monthly amount to figure your SSDI reduction.
Per SSA policy, a lump-sum settlement is prorated using the rate in the award, your prior periodic rate, or the state’s maximum weekly rate, in that order of priority.
When a settlement includes excludable expenses such as attorney fees or future medical costs, the SSA recognizes three proration methods. The rules for complex lump-sum awards lay them out:
- Method A: expenses are charged up front, which delays the start of the offset. Say a $60,000 award carries $10,000 in expenses and a $1,000 weekly rate. The first 10 weeks absorb the expenses, and the remaining $50,000 is prorated afterward.
- Method B: expenses are spread across the whole award, which lowers the weekly proration rate. The same award would be prorated at a reduced weekly rate over a longer stretch.
- Method C: expenses are subtracted from the end, which shortens the proration period. The $50,000 net amount is prorated at the full $1,000 weekly rate, ending after 50 weeks.
When the award does not say which method applies, the SSA is directed to consider all three and use the one most advantageous to you. Most cases run through automated systems, but when those cannot handle the case, staff prorate manually using Form SSA-2455 under POMS DI 52170.030.
Which states use reverse offset?
Reverse offset flips who absorbs the reduction. In 17 states and Puerto Rico, state law requires the workers’ compensation program to reduce its payments when you receive SSDI. In those jurisdictions, the SSA does not reduce your SSDI because the state has already handled the overlap.
For you, the practical difference is large. In a recognized reverse-offset state, your SSDI check stays whole and your workers’ comp benefit shrinks. In a non-reverse-offset state, the opposite happens.
Before you settle, take three steps:
- Read your state’s workers’ comp statute for any SSDI coordination language.
- Ask the SSA whether it recognizes your state’s reverse-offset law.
- Build that answer into your pre-settlement review so you model the right payer of the reduction.
State rules also affect which maximum weekly rate the SSA may use for proration. Our table of 2026 weekly benefit rates for all 50 states and DC is a handy place to confirm your state’s figure.
What should your settlement say before you sign?
Settlement wording matters, but only up to a point. The SSA is not bound by side agreements or addenda that try to label a lump sum in a way that avoids the offset. If it sees an attempt to circumvent the law, it can apply its own proration and offset methods instead of the language in your paperwork. Attempts to recast a lump sum as future medical costs can likewise be disregarded when the intent looks like offset avoidance.
What does help is accurate documentation. Attorney fees and genuine future medical costs, when itemized, can shorten the proration period under POMS DI 52150.060. Choosing Method C over Method A, for example, can mean a shorter offset window.
Work through this checklist before you sign:
- Request an explicit proration rate in the award.
- Itemize every excludable expense, with documentation.
- Run a proration estimate on a settlement calculator.
- Notify the SSA and request a proration worksheet.
- Have a workers’ comp attorney review the settlement.
- Keep records of every filing, payment and date.
Pro Tip: Ask your attorney to request, in writing, the proration method most favorable to you, and to document the judge’s approval where one is required.
Who qualifies for SSDI and workers’ comp, and why does it matter for offsets?
The two programs have different gatekeepers, and the offset only arises when you clear both. SSDI requires a work history with enough covered earnings and a medical condition that prevents substantial work and is expected to be long-term or result in death. Workers’ compensation, by contrast, requires that you were an employee and that your injury or illness arose out of and in the course of your job. It does not require a long work history or a year-long disability.
That difference explains why people so often land in both systems. A warehouse worker with a serious back injury may qualify for workers’ comp the day it happens and for SSDI months later once the SSA concludes the impairment will last. Once payments from both begin, the SSA looks at them together.
Not every payment counts for offset purposes. The rules apply to workers’ compensation and certain public disability benefits (PDB), and they hinge on whether the payment replaces lost earnings. Medical benefits paid directly to providers generally are not what the SSA is counting. Your state’s rules also shape who qualifies for workers’ comp and what you receive, and our state calculators reflect current caps. Understanding which program each payment belongs to is the first step in predicting any reduction.
How do you claim SSDI alongside workers’ comp?
You can pursue both at once, and in most cases you should. Here is a practical sequence.
- Report the injury and file the workers’ comp claim. Meet your state’s notice and filing deadlines, since missing them can forfeit benefits.
- Get medical documentation. Treating physicians’ records support both claims, and consistent records help avoid conflicting findings.
- Apply for SSDI early. The SSA’s review can take months, so there is no advantage to waiting for the workers’ comp case to resolve.
- Tell the SSA about your workers’ comp. On the application, disclose any workers’ comp claim, payments or settlement discussions. The SSA relies heavily on claimants to report this information, and GAO reviews found payment errors tied to unreported or changed workers’ comp benefits.
- Report changes promptly. A new weekly rate, a settlement, or the end of payments should reach the SSA fast.
- Model the offset before you settle. Run your numbers through a settlement calculator and review them with counsel.
Tracking dates and keeping copies of everything you send creates the paper trail you will want if the SSA’s calculation looks wrong later.
What challenges come up with SSDI offsets, and how do you handle them?
Most problems fall into a handful of patterns, and nearly all are easier to fix early.
Reporting gaps. The SSA depends on you to report workers’ comp changes. When reports are late or missing, the result is an overpayment the SSA later recovers, or an underpayment you never notice. GAO and SSA reviews have documented substantial errors of both kinds. Report every change in writing and keep proof of delivery.
Wrong ACE. If the SSA picks a lower ACE than it should, your ceiling drops and your offset grows. Request the calculation and compare it against your earnings record.
Unclear settlement language. An award that never states a proration rate or never itemizes expenses leaves the SSA to decide. Clear drafting up front prevents that.
Surprise overpayment notices. If you receive one, ask for a written explanation of how the SSA calculated the amount, and consider requesting reconsideration if the numbers look off. Our guide on how to avoid SSDI overpayments from workers’ comp walks through the warning signs.
Timing confusion. People often assume a lump sum is a one-time hit. In fact, the offset can stretch across the prorated period, so budget for a lower monthly SSDI check during that span.
When any of these arise, an attorney familiar with SSA coordination can often resolve in a single letter what would take months alone.

How do partial disability and vocational rehabilitation affect the offset?
Partial disability and retraining change what you collect from workers’ comp, and the SSA responds to the payment, not the label. If you receive permanent partial disability (PPD) benefits as periodic payments, they count toward the 80% test just as temporary total disability does. If your PPD is paid as a lump sum, the proration rules above apply.
A lower partial-disability rate can reduce or eliminate the offset, because the combined total may fall under your ACE ceiling. Conversely, a higher rate can push you over it.
Vocational rehabilitation is less clear-cut. Payments that replace wages while you retrain look like income replacement, whereas the cost of the training itself is a different kind of benefit. How the SSA treats a particular payment depends on what it replaces, so describe each component precisely in your paperwork and ask the SSA how it will be counted.
Returning to work adds another layer. SSDI has its own earnings rules, separate from the offset, and working while on partial disability can affect both programs at once. Because the interaction is technical, confirm with the SSA and your attorney before you accept a new position or enroll in a retraining program. Our impairment rating payout calculator can help you see what a given rating may be worth before you plan around it.
What happens when your workers’ comp benefits increase?
A rise in your workers’ comp rate generally means a bigger offset, not a bigger total. Because the cap is tied to your ACE, any increase in workers’ comp can push your combined benefits closer to or over that ceiling, and the SSA then trims SSDI to compensate. The net effect is that more workers’ comp does not always mean more money in your pocket.
If you were already at the ceiling, your SSDI could drop to keep the combined benefits within the limit. The figures here are hypothetical.
The reverse also holds. When workers’ comp ends or falls, the SSA should restore your SSDI. That restoration is not always automatic, which is another reason to report changes quickly.
Remember the floor, too: the offset cannot reduce your combined benefits below your original SSDI amount. And once you reach full retirement age, the offset ends and your Social Security is no longer reduced for workers’ comp.
If an increase is coming, run your updated numbers through your state’s TTD calculator so you can anticipate the change instead of discovering it on a benefit notice.
How does the 80% rule play out in real scenarios?
Walking through cases makes the rule concrete. All figures below are illustrative.
Scenario 1: no offset. If your combined SSDI and workers’ comp are below the applicable ceiling, nothing is reduced.
Scenario 2: partial offset. If your combined SSDI and workers’ comp exceed the applicable ceiling, the SSA reduces SSDI by the excess, subject to the applicable offset rules.
Scenario 3: lump sum under Method C. You settle for $60,000, with $10,000 in documented attorney fees and medical costs, at a $1,000 weekly rate. Under Method C, the SSA prorates $50,000 over 50 weeks. The offset applies for those 50 weeks, then ends, restoring your full SSDI.
Scenario 4: reverse-offset state. In a recognized reverse-offset jurisdiction, the state reduces workers’ comp instead of the SSA reducing SSDI.
Each case turns on the same three questions: what is your ACE, how are your benefits paid, and how does your state coordinate? Try your own figures in our lump-sum workers’ comp calculator to see where you fall.

Why we built a 50-state calculator for this problem
Here is where we stand on this. We think a realistic estimate beats a guess. That is why we calibrate our calculators to 2026 state caps for all 50 states, so the numbers you test reflect current limits. Use them to sharpen the questions you bring to your attorney and the SSA, not to replace either. A calculator is a planning aid, and it is never legal advice.
— Daniel
How can you estimate offsets and settlements with our calculator?
We built our free calculators to help you model outcomes before you negotiate or call the SSA. They apply 2026 state benefit caps and include weekly TTD and PPD estimators, lump-sum scenario models and impairment-specific tools.
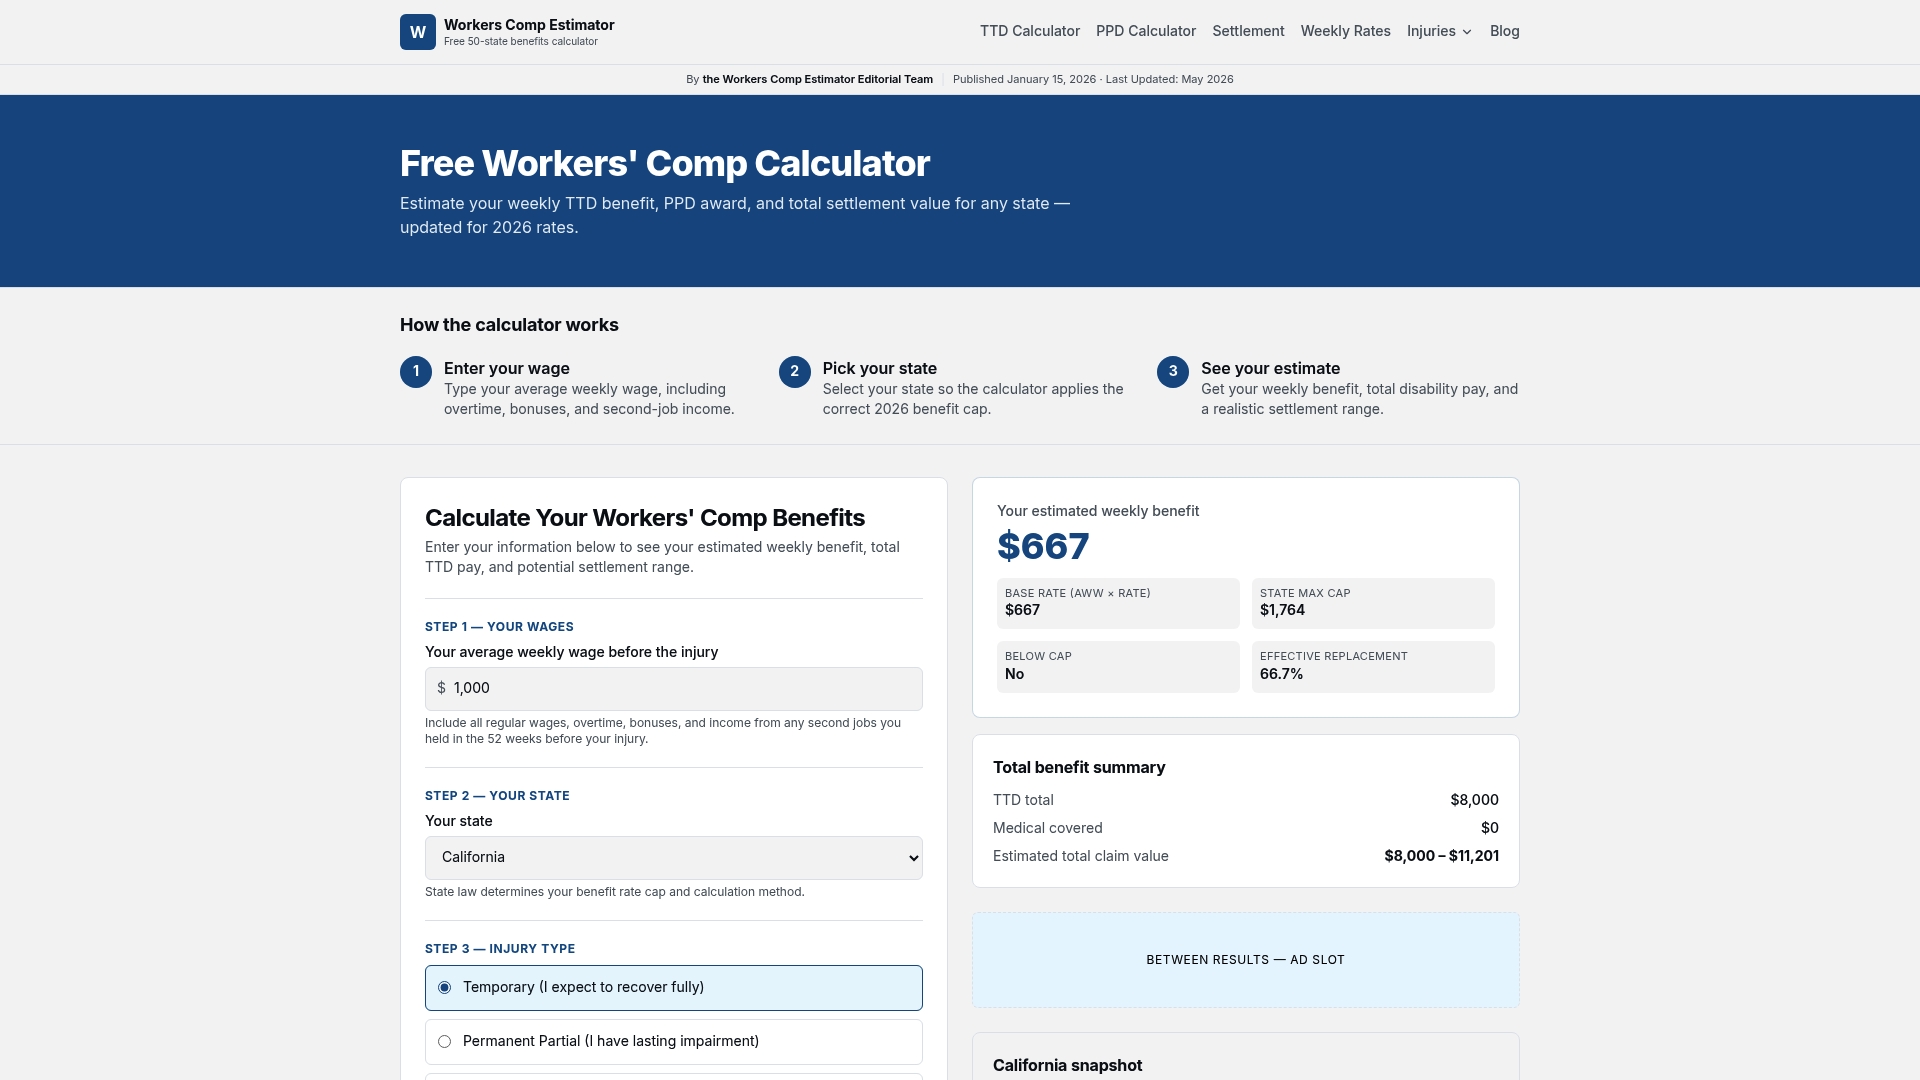
A simple workflow:
- Run your state’s calculator, such as the Texas or Ohio version, or start from our main 50-state estimator.
- Estimate your ACE from your earnings history.
- Model lump-sum proration scenarios in the settlement calculator.
- Bring the results to your attorney and your SSA contact.
These are planning estimates. The SSA makes the final proration and offset determination. Start with your state’s calculator today and walk into your next conversation with numbers in hand.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Does workers’ comp count as income for Social Security?
Workers’ comp does not count as earned income for SSDI work tests, but it does trigger the offset when combined with SSDI. The SSA reduces your SSDI if the combined total passes 80% of your average current earnings.
What does offset mean in disability benefits?
An offset is a reduction in one benefit because you receive another. The reduction cannot drop your combined benefits below your original SSDI amount.
Does a lump-sum settlement avoid the offset?
No. The SSA treats a lump sum as a substitute for periodic payments and prorates it over time. The offset generally applies only during the prorated period, and documented excludable expenses can shorten it.
When does the offset end?
It ends when your periodic workers’ comp payments stop, when the lump-sum proration period runs out, or when you reach full retirement age. It also does not apply if your state has a recognized reverse-offset law, since the state then reduces workers’ comp instead.
Sources
- Secure
- GAO-01-367 Workers’ Compensation: Action Needed to Reduce Payment Errors in SSA Disability and Other Programs
Recommended
More from the blog
Use the free 50-state estimator that applies 2026 state caps to estimate your workers' comp lump sum. Run your numbers, check SSDI/Medicare impact, and...
Learn how Texas workers’ comp impairment ratings affect benefits, deadlines, and disputes, then use the payout calculator before accepting an offer.
Learn what drives U.S. hip workers' comp settlement value. Use the $66,634 benchmark, avoid WCMSA mistakes, meet state deadlines, and run a 50 state...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.