Avoid SSDI Overpayments From U.S. Workers’ Comp Using a Free 2026 Calculator

Yes, you can receive workers’ compensation and SSDI at the same time, but the Social Security Administration will often reduce your SSDI when combined monthly payments exceed the higher of 80% of your average current earnings or your pre-offset SSDI amount. Lump-sum settlements usually get prorated into a monthly figure for this calculation, though documented legal and medical expenses can reduce that number. Report any workers’ comp payment to SSA and keep every piece of settlement paperwork.
TL;DR:
- SSA reduces SSDI benefits when combined monthly payments from workers’ compensation and SSDI exceed the higher of 80% of pre-disability earnings or the unreduced SSDI amount.
- Lump-sum settlements are prorated into a monthly equivalent for offset calculations, with certain medical and legal expenses deductible if properly documented in the settlement agreement.
- States may apply reverse-offset rules, reducing workers’ comp payments instead of SSDI, depending on specific state laws and SSA policies.
- Reporting all workers’ compensation payments and settlements promptly to SSA is essential to avoid overpayment and future recovery issues.
- Using a workers’ comp calculator before settling helps injured workers estimate their potential offset and plan accordingly.
Table of Contents
- Can you collect SSDI and workers’ compensation at the same time?
- How SSA computes the offset: the 80% rule and average current earnings
- Lump-sum settlements: proration, excludable expenses, and pitfalls
- State variability and reverse-offset rules
- What to report to SSA and how to avoid overpayment recovery
- Using a workers’ comp calculator and a documentation checklist
- An injured worker’s practical priorities
- Free Workers’ Comp Calculator: estimate your exposure before you settle
- FAQ
- Sources
Can you collect SSDI and workers’ compensation at the same time?
Workers’ compensation comes from state law and covers job-related injuries, while SSDI is a federal program tied to a long-term disability that keeps you from working. Because they serve different purposes and come from different systems, nothing stops you from qualifying for both. The catch is that SSA treats your combined monthly income from both programs as a single pool subject to a cap.
Several types of workers’ comp payments can trigger this offset:
- Periodic total temporary disability (TTD) payments received while your claim is open.
- Permanent partial disability (PPD) or permanent total disability (PT) awards paid on a schedule.
- Lump-sum settlements that substitute for what would otherwise have been periodic payments.
A common scenario looks like this: someone receives weekly TTD checks from their employer’s insurer while also drawing SSDI for the same injury, and SSA reduces the SSDI check to keep the combined total under the legal limit. Another common scenario happens when a worker already receiving SSDI settles their workers’ comp claim for a lump sum, which SSA then converts into a monthly rate for the same offset math.
How SSA computes the offset: the 80% rule and average current earnings
Section 224 of the Social Security Act, implemented through 20 CFR 404.408, sets the framework SSA uses to decide whether your SSDI gets reduced. SSA compares two numbers: 80% of your “average current earnings” before you became disabled, and your total unreduced SSDI benefit (including amounts payable to your family). Whichever of those two numbers is higher becomes the ceiling; if your workers’ comp plus your SSDI exceeds that ceiling, SSA trims the SSDI down to fit.
“Average current earnings” is not simply your last paycheck. SSA calculates it using one of three methods:
- The average monthly wage used to figure your disability benefit.
- The average monthly earnings from your highest five consecutive years of earnings.
- The average monthly earnings from your single highest earning year in the five years before you became disabled.
SSA uses whichever method produces the highest figure, which can push the 80% ceiling well above what your current income would suggest.
80% is the operative threshold in nearly every offset case. The governing regulation caps combined benefits at the higher of 80% of average current earnings or total unreduced SSDI, meaning a worker with high pre-injury earnings can sometimes absorb a sizable workers’ comp payment with little or no SSDI reduction.
Lump-sum settlements: proration, excludable expenses, and pitfalls
When a workers’ comp claim settles for a lump sum instead of continuing weekly payments, SSA cannot just divide that payment by zero months. Instead, SSA prorates the settlement into a monthly equivalent using POMS guidance on prorating lump-sum settlements, which covers structured settlements, advance payments, and any addenda that amend the original agreement. If the settlement specifies a monthly rate, SSA generally uses it; if it does not, SSA will fall back to a prior periodic rate or the state’s maximum weekly benefit rate to approximate one.
Not every dollar in a settlement counts against you. According to SSA’s rules on excludable expenses, certain costs can be subtracted from the settlement total before SSA calculates the offset:
- Attorney’s fees and litigation costs tied directly to the claim.
- Medical expenses related to the injury, including future medical costs.
- Properly documented Medicare Set-Aside Arrangements (MSAs).
The expenses have to be itemized in the award or compromise agreement itself. A verbal understanding or an attorney’s later explanation carries far less weight than language written into the settlement document at the time it’s signed.
This is also where claimants run into trouble. SSA has shown it will disregard settlement language added after the fact if it looks designed to dodge the offset, a position reflected in longstanding precedent on compromise lump-sum settlements.
Pro Tip: Ask your attorney to itemize legal fees, medical costs, and any MSA amount directly in the settlement agreement, not in a side letter, before you sign anything.

State variability and reverse-offset rules
Not every state lets SSA reduce the SSDI check. In certain states, the law instead reduces the workers’ comp payment itself, a setup known as reverse offset, which leaves SSDI untouched while the state benefit absorbs the reduction. Whether this applies to you depends entirely on your state’s workers’ comp statute, and SSA’s own POMS system includes state-specific pages, such as the one covering West Virginia, that spell out how each state’s system is treated.
Before assuming either way, verify your state’s status directly:
- Check SSA’s POMS state-specific pages for your state’s treatment.
- Review your state’s workers’ comp statute or ask your state agency directly.
- Confirm with a workers’ comp attorney familiar with your state, since state-level benefit structures vary considerably even among neighboring states.
- Request written confirmation of your award amount and payment schedule from your carrier.
What to report to SSA and how to avoid overpayment recovery
SSA needs to know about your workers’ comp at several points: when you first apply for SSDI, whenever your workers’ comp status changes, and immediately upon receiving a lump-sum settlement. Follow these steps to stay ahead of problems:
- Report any workers’ comp award or settlement to SSA as soon as it’s finalized, using the reporting forms and procedures your local SSA office provides.
- Keep a complete, itemized copy of the settlement award or court order, since SSA will request it to calculate proration.
- Contact your insurer or third-party administrator for written confirmation of the payment schedule and any monthly-equivalent rate.
- Run the numbers yourself before signing anything, so you know roughly what offset to expect.
SSA often discovers unreported workers’ comp through state records or third-party reporting rather than waiting on claimants to volunteer it, and a GAO review of SSA’s administration found that reliance on self-reporting and fragmented state systems contributes to payment errors. That means an unreported settlement can surface months later as an overpayment notice demanding repayment.
Pro Tip: Report the moment you sign a settlement, even if the check hasn’t arrived yet, since SSA counts the award date, not the payment date, in most proration calculations.
Using a workers’ comp calculator and a documentation checklist
Before you settle, it helps to see the numbers laid out. Our free workers’ comp calculator estimates weekly TTD and PPD benefits using each state’s 2026 caps, along with potential lump-sum settlement equivalents, so you can anticipate how SSA might prorate a settlement. Running a scenario before signing gives you a realistic monthly-equivalent figure to compare against SSA’s offset math, and it highlights exactly which settlement items (monthly rate, itemized expenses, carrier contact) you need in writing.
An injured worker’s practical priorities
Document everything from day one: award letters, medical bills, attorney fee statements, and any correspondence with your carrier. Disclose every workers’ comp payment to SSA promptly rather than waiting for a letter asking why you didn’t. If your settlement language around excludable expenses feels vague, have an attorney review it before you sign, since a clean estimate is only useful if the paperwork behind it holds up.
— Daniel
Free Workers’ Comp Calculator: estimate your exposure before you settle
We built our free workers’ comp calculator because most injured workers settle a claim without ever seeing a realistic number for what they’re giving up or what SSA might later claw back. Our tool uses each state’s benefit caps, so the weekly TTD and PPD figures it returns reflect current limits rather than outdated averages.
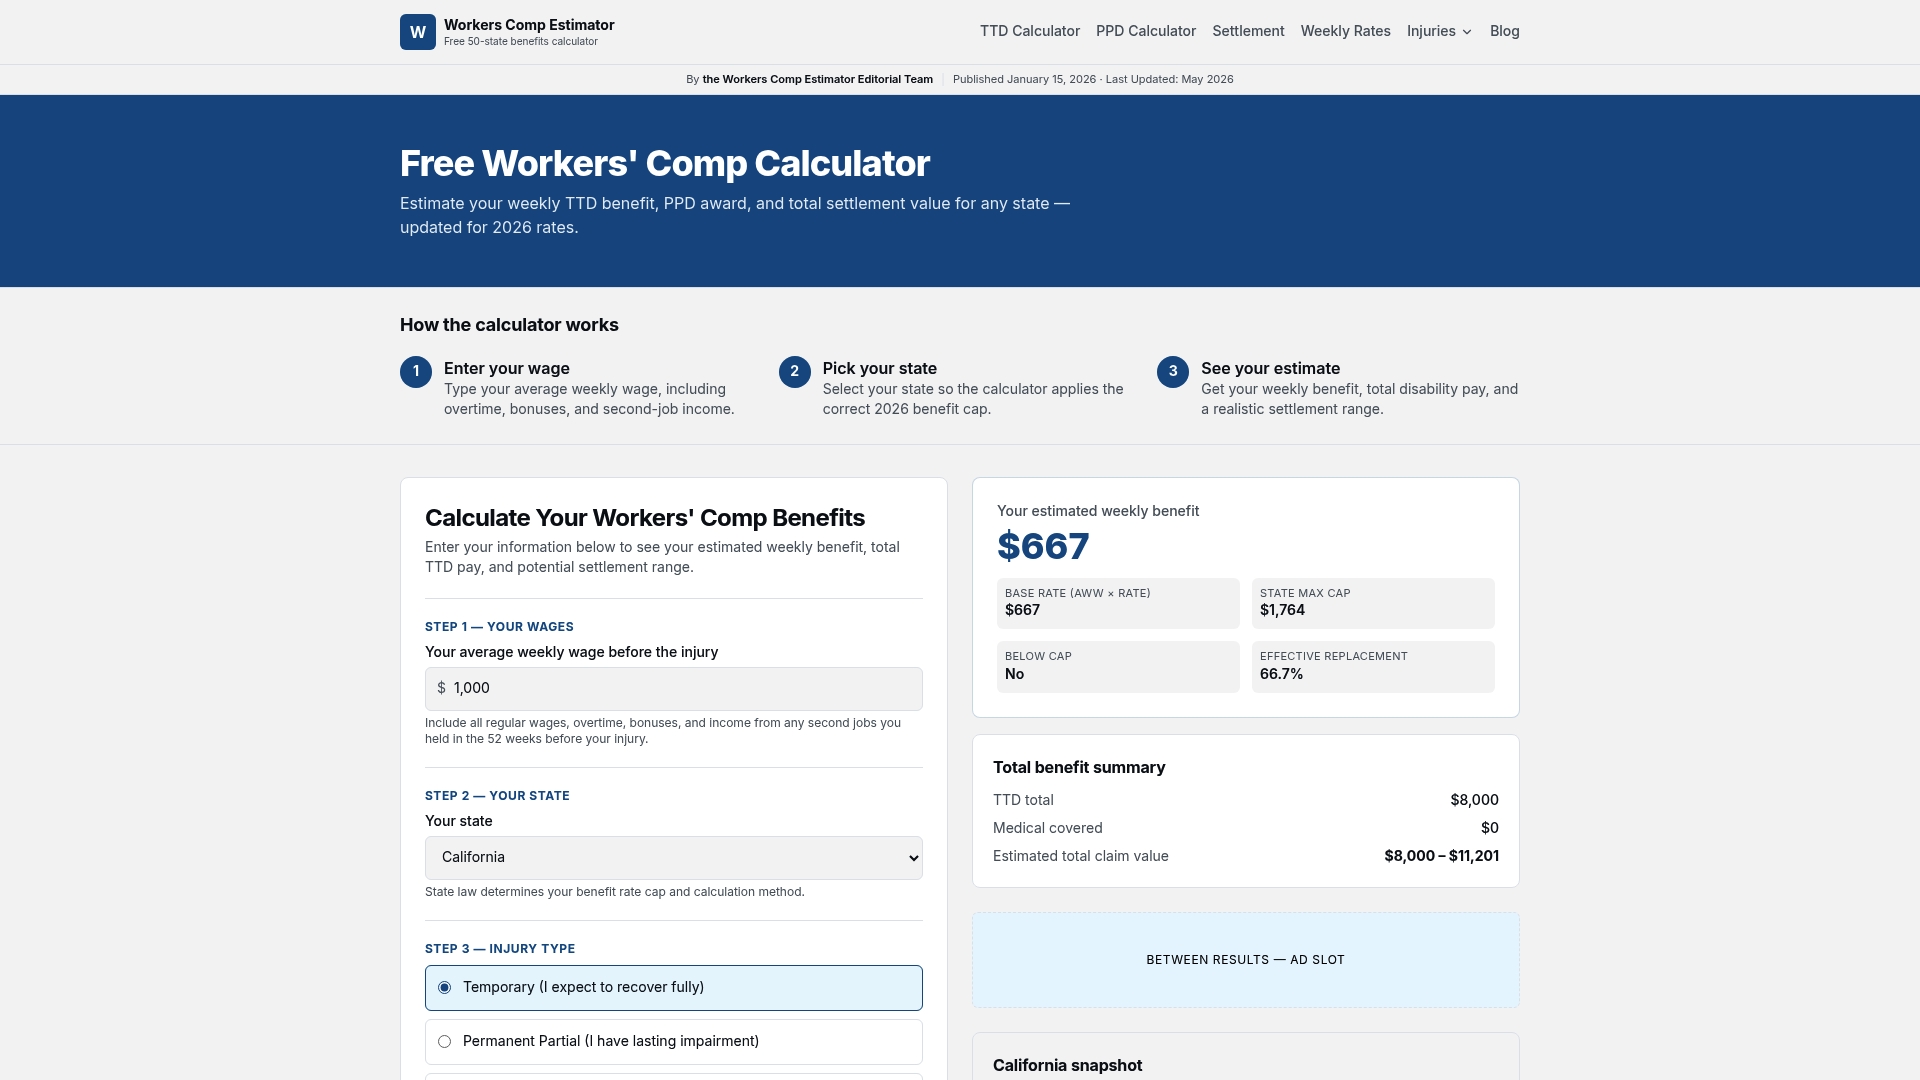
Before you sign a settlement or report a lump sum to SSA, it’s worth running the scenario through our settlement calculator to see a monthly-equivalent estimate you can compare against SSA’s offset formula.
- Estimate weekly TTD and PPD benefits using your state’s actual 2026 caps.
- See a lump-sum settlement equivalent before you finalize paperwork with your carrier.
- Check your state’s weekly benefit rate to confirm what maximum SSA might use if your settlement lacks a specified rate.
Start with our workers’ comp calculator to get a clear estimate before your next conversation with your attorney or insurance adjuster.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can I collect SSDI and workers’ comp at the same time?
Yes, you can receive both, but SSA may reduce your SSDI when the combined monthly total exceeds the higher of 80% of your average current earnings or your unreduced SSDI amount, under 20 CFR 404.408. Some states apply a reverse offset that reduces the workers’ comp payment instead, leaving SSDI untouched.
Will a workers’ comp settlement affect my SSDI?
A lump-sum settlement is typically prorated into a monthly equivalent and factored into SSA’s offset calculation, following SSA’s proration rules. Itemized legal and medical expenses listed in the settlement agreement can be excluded from that calculation, which lowers the effective monthly amount SSA counts.
How much money am I allowed to make while on Social Security disability?
This question usually concerns SSDI’s substantial gainful activity rule for work income, which is separate from the workers’ comp offset discussed here. The workers’ comp and SSDI offset instead caps your combined benefit income at 80% of your average current earnings or your pre-offset SSDI, whichever is higher, under section 224’s implementing regulation.
Can you collect Social Security while on workers’ comp?
Yes, concurrent receipt is allowed, but SSA applies the 80% offset rule described in 20 CFR 404.408 unless your state has a reverse-offset arrangement that reduces your workers’ comp payment instead. Reporting your workers’ comp to SSA promptly helps avoid an overpayment notice later.
Sources
- SSA - POMS: DI 52150.060 - Prorating a Workers’ Compensation/Public Disability Benefit (WC/PDB) Lump Sum Settlement
- 20 CFR § 404.408 - Reduction of benefits based on disability on account of receipt of certain other disability benefits
Recommended
More from the blog
Use the free 50-state estimator that applies 2026 state caps to estimate your workers' comp lump sum. Run your numbers, check SSDI/Medicare impact, and...
Run a state specific 2026 workers' comp settlement calculation. Use the free 50 state calculator to see how state caps change your payout.
Compare workers' comp and disability for U.S. workers: what each pays, SSDI's five-month wait, tax rules, and a free 50-state calculator to estimate your...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.