Bring State Accurate Numbers to U.S. Workers’ Comp Mediation

Workers’ compensation mediation is a neutral settlement meeting where a trained mediator helps you and the insurance company resolve a disputed claim without going to a hearing. Most sessions end with either a signed agreement or a clear next step toward a hearing. Coming prepared with medical records, wage documentation, and realistic settlement numbers, plus awareness of Medicare set-aside rules, makes a real difference in how the session goes.
TL;DR:
- Having organized medical and wage records, along with a credible settlement number based on state-adjusted calculators, significantly improves negotiation leverage.
- Mediation is often required or encouraged before hearings, typically lasting two to four hours and involving private caucuses that protect confidential information.
- Including a Medicare set-aside allocation in your settlement plan is crucial, as improper handling can result in Medicare refusing future payments or seeking recovery.
- Self-representation is feasible for straightforward claims with modest values, but complex cases benefit from legal advice to navigate dispute resolution and Medicare considerations.
- Presenting a detailed, calculator-derived settlement range backed by concrete documentation shifts the tone of negotiations and reduces the risk of lowball offers.
Table of Contents
- What is workers’ compensation mediation?
- What happens during a mediation session
- How to prepare for mediation
- Do I need a lawyer for mediation?
- Settlement outcomes and Medicare considerations
- Using the calculators to walk in with real numbers
- A practical way to think about mediation
- Try the Workers’ Comp Calculator before mediation
- Sources
- FAQ
What is workers’ compensation mediation?
Mediation is a facilitated settlement conference. A neutral third party, often a staff mediator from a state alternative dispute resolution office or an assigned judge, sits between you and the insurance company to help both sides find common ground. The mediator does not decide who wins. They ask questions, point out weaknesses in each position, and shuttle offers back and forth until a deal forms or talks stall.
Some states require mediation before a hearing can be scheduled. Others make it optional, something either party can request when a claim stalls over disputed medical treatment, average weekly wage, or the value of a permanent disability. Rules and terminology vary by state: some call it a settlement conference, others a pre-hearing conference, but the format is largely the same.
Most state industrial commissions or workers’ comp boards offer mediation through their own ADR programs at no cost to either party. Private mediators exist too, usually hired when both sides want someone outside the state system, but that option comes at the parties’ own expense.

What happens during a mediation session
Mediation sessions typically run two to four hours and follow a predictable pattern, though the mediator sets the pace.
- Opening statements. Each side, usually through an attorney or representative, briefly summarizes the dispute and what they are seeking.
- Private caucuses. The mediator separates the parties into different rooms and moves between them, testing settlement flexibility without either side hearing the other’s private concerns.
- Exchange of offers. Numbers move back and forth through the mediator, often several rounds, as both sides narrow the gap.
- Agreement or impasse. If the numbers converge, the mediator helps draft settlement terms on the spot. If they do not, the case heads toward a scheduled hearing.
The people in the room usually include you, your attorney or representative if you have one, the insurance adjuster or a company representative, and the mediator. Everything said in caucus and joint session is confidential and generally cannot be used against you later if the case goes to a hearing. Once a settlement is signed, though, it becomes a binding document once the commission or board reviews and approves it, and at that point it is a matter of public record.
How to prepare for mediation
The strongest position at mediation belongs to the side with organized documentation and a credible number, not the side with the loudest argument.
Bring these items:
- Medical reports and treatment notes covering the full course of your injury.
- Billing and payment records for medical care already provided.
- Wage statements showing your average weekly wage before the injury.
- Employer incident reports and any correspondence about the claim.
- Prior settlement offers or demand letters exchanged so far.
- Vocational or independent medical examination (IME) reports if they exist.
Before you walk in, run your numbers. The settlement calculator lets you plug in your average weekly wage, state, and injury type to model a low, target, and high settlement range instead of guessing. If a state-specific benchmark helps, tools like the Massachusetts calculator, Oregon calculator, or California calculator show how state caps shape your specific numbers, and the PPD calculator helps estimate a permanent partial disability award if that applies to your injury.
If Medicare eligibility is anywhere in the picture, think about how a settlement would split between past medical bills, future medical care, and wage loss before you arrive. That allocation matters more than most workers realize.
Pro Tip: Keep your opening number defensible. A round figure with no backup invites a lowball counter; a number tied to your wage records and a calculator printout is harder to dismiss.
In the room, stick to facts in joint session and save flexibility for private caucus with the mediator. Avoid ultimatums, avoid discussing settlement authority limits out loud, and never let frustration turn a negotiation into a personal argument with the adjuster.
Do I need a lawyer for mediation?
Representation tends to pay off when the case is complicated: disputed liability, a high permanent disability rating, conflicting medical opinions, or any scenario where Medicare’s future interest in your care needs protecting. An attorney who handles these cases regularly knows how adjusters value claims and where the real negotiating room is.
Self-representation can be reasonable for smaller, cleaner claims: liability is not contested, medical treatment is simple, and the dollar amounts involved are modest enough that legal fees would eat a meaningful share of any gain.
If you cannot retain full representation, a single paid consultation before mediation, just to have someone review a specific settlement offer, is often enough to catch a lowball number or a missing allocation before you sign anything.
Settlement outcomes and Medicare considerations
Mediation ends one of three ways: a full settlement signed that day, a conditional agreement pending some follow-up detail like a final medical report, or no agreement, which sends the claim toward a scheduled hearing.
When Medicare enters the picture, the settlement needs closer attention.
- A Workers’ Compensation Medicare Set-Aside (WCMSA) allocates part of a settlement specifically for your future Medicare-covered medical care.
- If a WCMSA is required and the funds are not properly exhausted first, Medicare can refuse to pay for related care until that money runs out, according to the CMS WCMSA reference guide.
- CMS review may apply based on whether you are already a Medicare beneficiary or reasonably expected to enroll within 30 months of settlement, alongside certain settlement-size thresholds described in the same CMS guide.
Failing to account for Medicare’s interest in a settlement can allow CMS to seek recovery directly from the settlement proceeds, per CMS recovery guidance, which is exactly why the medical allocation deserves as much attention as the total dollar figure.
Whether your case is structured as a commutation or a compromise settlement changes how CMS treats the review, a distinction laid out in a CMS regional memorandum on commutation versus compromise settlements. Where liability was never disputed, WCMSAs are more commonly used; where liability was contested, the documentation supporting your allocation carries more weight.
Using the calculators to walk in with real numbers
Turning your records into a number the adjuster respects takes three steps: find your state’s calculator page, enter your wage and injury details, and run a settlement scenario. The output shows your estimated weekly TTD or PPD benefit under your state’s 2026 cap alongside a modeled settlement range you can print and bring to the table.

Adjusters expect specific figures tied to actual wage data and state limits, not a vague ask. A printed calculation changes the tone of the conversation before anyone even sits down.
A practical way to think about mediation
Mediation rewards preparation over emotion. The side that shows up with medical records, wage documentation, and a calculated settlement range controls more of the outcome than the side that shows up with a grievance.
Protect the medical allocation first. A number that looks generous but leaves future care underfunded is not a win. Anchor every argument in documents and figures, not in how unfair the injury feels, because the adjuster across the table is negotiating from numbers whether you are or not.
— Daniel
Try the Workers’ Comp Calculator before mediation
Walking into mediation with a documented, state-accurate number is one of the simplest ways to shift a negotiation in your favor. The Workers’ Comp Calculator uses each state’s 2026 benefit caps to turn your wage and injury details into a realistic weekly benefit and settlement estimate you can bring straight into the room.
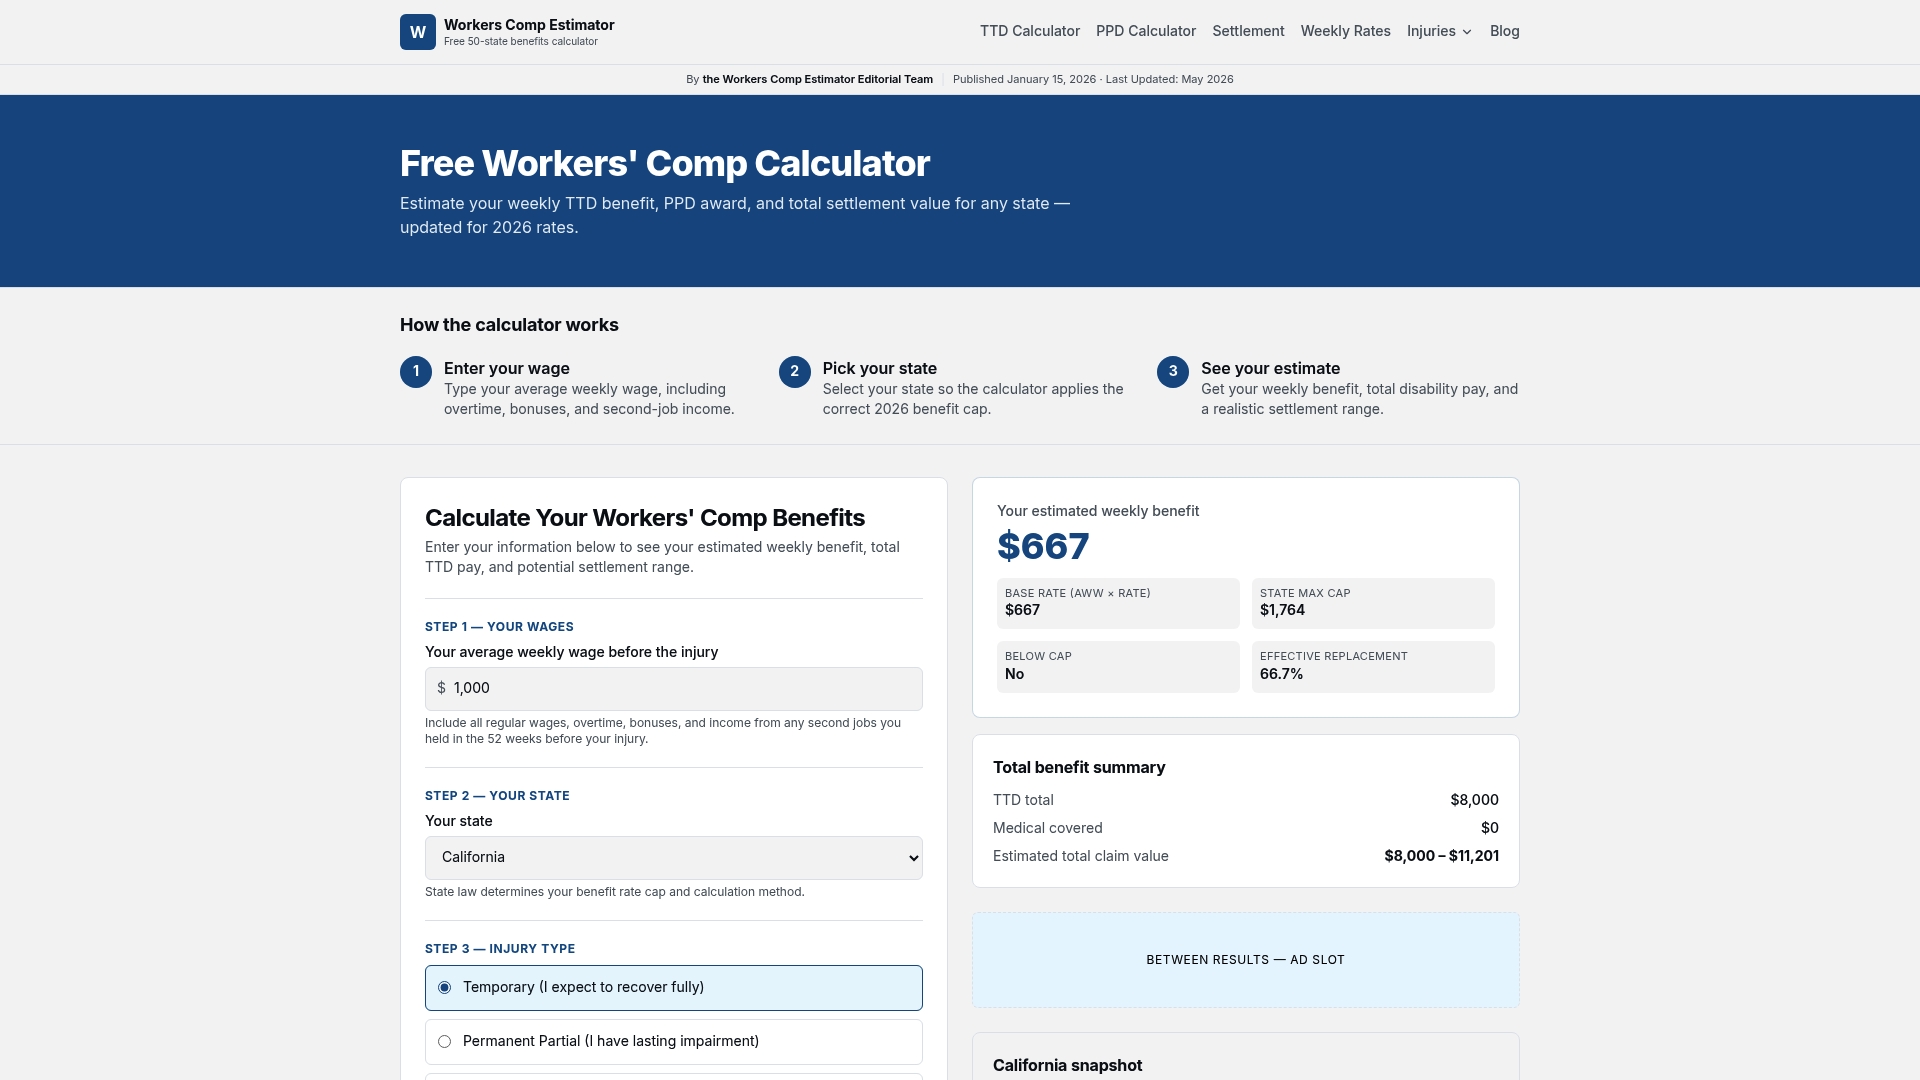
Start with your state page, run the numbers for your average weekly wage and injury type, then use the settlement calculator to build your low, target, and high range before your session. If a permanent disability rating applies, check the PPD calculator too so your allocation reflects the full picture.
Sources
For deeper reading: the CMS WCMSA reference guide covers Medicare set-aside rules, and Nccertifiedparalegal offers state-specific procedural notes for claim paperwork.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- WCMSA reference guide v.4.4 (CMS)
FAQ
What percentage of workers’ comp cases settle during mediation?
There is no single nationwide figure, since outcomes vary widely by state, mediator, and case type. What is consistent across practice guidance is that cases with organized documentation and realistic settlement numbers tend to resolve more successfully than those without.
What happens in a work comp mediation?
A neutral mediator meets with you, your representative if you have one, and the insurance adjuster, moving between private caucuses and joint discussion to test settlement offers. The session typically ends in a signed agreement, a conditional agreement pending a follow-up step, or no deal, which sends the case toward a hearing.
What are the three rules for mediation?
Definitions vary, but most mediation programs share three core principles: the mediator stays neutral and does not decide the outcome, communications during the session stay confidential, and participation only becomes binding once an agreement is signed and formally approved.
What not to say during mediation?
Avoid stating your absolute bottom line, your settlement authority limits, or anything that sounds like an ultimatum in joint session, since that information can weaken your negotiating position once shared. Save flexible numbers and concerns for private caucus with the mediator instead of the open room.
Recommended
More from the blog
U.S. guide for Medicare eligible claimants: see the $25,000/$250,000 CMS review triggers, learn funding and admin options, and use free 50 state...
U.S. injured workers: see when insurers make offers, how state caps change value, and use free calculators to test your settlement numbers before you sign.
Use the free 50-state estimator that applies 2026 state caps to estimate your workers' comp lump sum. Run your numbers, check SSDI/Medicare impact, and...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.