Use 2026 State Caps to Calculate Your Permanent Restrictions Settlement

Insurers usually wait until you reach Maximum Medical Improvement and receive a permanent impairment rating before making a serious offer. Permanent restrictions typically raise a settlement’s potential value, but they also make insurers slower to commit until future medical and wage costs are clearer. Your real choice is between a lump sum that closes future benefits and a limited settlement that preserves ongoing medical care, and the right answer depends heavily on your state’s caps and rules, so running state-specific numbers before you negotiate matters.
TL;DR:
- Settlement offers typically come after your doctor issues a final impairment rating and your medical file is closed, with early low offers being common.
- Higher impairment ratings and permanent restrictions generally increase settlement values, but they also introduce more long-term uncertainty for insurers.
- Full-and-final lump-sum settlements permanently close your claim and benefits, so it’s crucial to clarify whether medical and medical liens remain open before agreeing.
- Running your own benefit and impairment calculations using state caps and tools helps establish realistic negotiation benchmarks and avoid undervaluation.
- Settlement impacts your future benefits and employment options, including potential reductions in other disability programs and the need for employer accommodations.
Table of Contents
- When insurers usually make settlement offers: MMI, stabilization, and timeline
- How permanent restrictions and PPD awards change settlement value
- Lump-sum settlements vs keeping future medical benefits: what you give up and how to protect yourself
- How to evaluate a settlement offer: a short checklist for injured workers
- State variation and examples: where rules or caps change the math
- Tools and calculations: using benefit and PPD calculators to estimate settlement ranges
- Legal implications and rights when accepting a permanent restrictions settlement
- Common negotiation strategies for permanent restrictions settlements
- Impact of permanent restrictions settlement on long-term disability benefits and employment
- Tax considerations related to lump-sum settlements for permanent restrictions
- Author perspective: balancing immediate needs with long-term security
- Use the free calculators to estimate your settlement range
- FAQ
- Sources
When insurers usually make settlement offers: MMI, stabilization, and timeline
Maximum Medical Improvement, or MMI, is the point where your doctor determines your condition has stabilized and further treatment is unlikely to produce meaningful improvement. Once you hit MMI, a physician assigns a permanent partial disability (PPD) rating, often called an impairment rating, that quantifies how much function you have permanently lost.
Insurers lean on MMI and PPD ratings because these are the only reliable inputs for estimating what your claim will cost long term. Before MMI, future medical bills and lost earning capacity are too uncertain to price into an offer, so serious settlement talks almost always wait until these benchmarks are set.
Common milestones along the way include:
- An independent medical examination (IME) requested by the insurer to confirm or challenge your treating doctor’s findings.
- Formal issuance of a PPD or impairment rating once your condition is deemed stable.
- A vocational assessment if your restrictions affect your ability to return to your prior job.
- Resolution of any disputed or unresolved medical treatment that could still change your prognosis.
A real offer is more likely once your rating is final and your medical file is closed. Watch for exceptions: some insurers float early, low offers to settle cheap before your rating is set, especially when a worker seems eager to resolve the claim quickly.
How permanent restrictions and PPD awards change settlement value
Permanent restrictions change settlement math because they shift a claim from short-term wage replacement into long-term compensation for lost function and earning capacity. How that translates into dollars depends on whether your injury falls under a scheduled award or a non-schedule, whole-body impairment.
Scheduled awards apply to specific body parts, like a hand, arm, or leg, with payouts set by a formula tied to your state’s statute. Non-schedule injuries, such as back or psychological conditions, are often rated as whole-body impairment (WBI) and tend to involve more negotiation because they don’t fit a fixed table.
A settlement figure built around permanent restrictions typically includes:
- Past indemnity owed, covering any unpaid wage-replacement benefits up to the settlement date.
- Future wage loss, estimated from your restrictions and ability to return to comparable work.
- The PPD award itself, based on your impairment percentage and state formula.
- Future medical costs, if the settlement includes an allocation for ongoing care.
- Vocational rehabilitation costs, when retraining is likely due to your restrictions.
- Age and life-expectancy adjustments, since younger workers with permanent restrictions face more years of reduced earning capacity.
Workers with higher whole-body impairment ratings tend to face delayed return-to-work and higher reinjury risk, which research funded by the CDC ties to poorer long-term employment outcomes. That pattern cuts both ways in negotiations: a higher rating generally supports a larger settlement number, but it also means more uncertainty about future costs, which can make insurers cautious about committing to a final figure too early.
Lump-sum settlements vs keeping future medical benefits: what you give up and how to protect yourself
A full-and-final settlement closes your claim completely: you receive a lump sum, and in exchange you give up the right to reopen the case for additional indemnity or medical benefits, even if your condition worsens. A limited or partial settlement resolves only specific issues, like disputed indemnity, while leaving your medical benefits open. The wording in your stipulation decides which one you’re signing, so read it carefully rather than assuming based on what someone tells you verbally.
Common pitfalls include:
- Future medical funds allocated too thinly to cover realistic long-term care costs.
- Unresolved Medicare conditional payment issues that can delay or complicate your settlement.
- Outstanding medical liens that reduce your net recovery if not addressed before signing.
- Vague release language that unintentionally closes benefits you intended to keep open.
To protect yourself, ask for explicit medical carve-outs in the stipulation, a clearly defined allocation for future medical within the lump sum, or a structured settlement that pays out over time instead of all at once. Resolving liens before you sign, rather than after, keeps your final payout predictable.
Pro Tip: Have an attorney or a vocational and medical advisor review the stipulation line by line before you sign anything that touches future medical care.
How to evaluate a settlement offer: a short checklist for injured workers
Before you accept any number, work through a short sequence of checks so you know exactly what you’re agreeing to:
- Confirm your MMI status and PPD rating are finalized and documented in writing.
- Request an itemized breakdown of the offer showing indemnity, PPD, and medical components separately.
- Verify your average weekly wage (AWW) was calculated correctly, since errors here distort everything downstream.
- Ask directly whether medical benefits are closed or remain open after the settlement.
- Check for liens or third-party offsets, including Medicare conditional payments, that could reduce your net amount.
- Confirm whether future medical care is addressed, and if so, how the allocation was calculated.
Gather your medical records, any IME report, a vocational assessment if one exists, and a current lien ledger before you respond to an offer. If any of these pieces are missing or your condition still seems unstable, it’s reasonable to delay signing. When the numbers feel unclear or the stakes are high, running your own calculations and talking to counsel before you respond puts you in a stronger position than reacting to the insurer’s first number.
State variation and examples: where rules or caps change the math
Workers’ compensation is governed state by state, and that creates real differences in settlement outcomes even for similar injuries. Weekly benefit caps, scheduled-award formulas, whether lump sums are common practice, and the availability of vocational programs all shift what a fair number looks like.
- Weekly benefit maximums vary widely. Connecticut’s 2026 cap sits near $1,897 per week while Rhode Island’s sits near $1,625, so identical wage-loss claims produce different weekly indemnity figures depending on where you’re injured.
- Settlement practices themselves shift over time. A WCRI FlashReport on New York’s settlement behavior found that changes in policy and practice altered how often and how quickly lump-sum settlements with indemnity and medical components occurred.
- Scheduled-award formulas for the same body part can produce different dollar amounts depending on the state’s statute and wage base.
Because these variables compound quickly, running your numbers through a state weekly benefit rate table before negotiating gives you a realistic starting point instead of a guess.
Tools and calculations: using benefit and PPD calculators to estimate settlement ranges
Before you negotiate, it helps to test your own numbers rather than relying solely on the insurer’s math. Key inputs include your average weekly wage, your PPD rating or scheduled award, your state’s weekly benefit cap, anticipated future medical costs, and your age.
A simple way to stress-test an offer is to run three scenarios:
- Base case: current benefits and rating as documented today.
- Conservative case: higher future medical costs if your condition could worsen.
- Optimistic case: lower future costs assuming a faster return to comparable work.
A PPD calculator or settlement calculator can estimate likely ranges for each scenario, but the output is not a legal release and doesn’t replace a signed agreement. Use the numbers to prepare sharper questions and to ground your conversation with an attorney in specifics rather than vague impressions.
Legal implications and rights when accepting a permanent restrictions settlement
Signing a settlement is voluntary, but once it’s approved by your state’s workers’ comp board or court, it typically becomes binding and difficult to reopen. You retain the right to review the stipulation, negotiate its terms, and decline an offer that doesn’t reflect your actual medical and financial needs. No one can force you to settle before you’re ready, though insurers may apply pressure through repeated low offers or delays in authorizing treatment.
The core legal question in any settlement is what exactly gets released. A full-and-final agreement typically ends your right to reopen the claim even if your condition deteriorates later, while a partial settlement leaves specific benefits, often medical care, available going forward. Because this distinction is defined by the exact language in your stipulation rather than by general custom, you have the right to request changes to that language before signing.
You also retain rights related to liens and reimbursements. Medical providers, health insurers, or Medicare may have a claim against your settlement for payments already made, and resolving these before finalizing the agreement protects your net recovery. If your settlement involves an allocation for future medical care, Medicare’s conditional payment review process may need to be addressed so future claims aren’t denied due to an inadequate set-aside.
Workers who settle while represented by an attorney typically have more leverage to negotiate protective language into the stipulation. If you’re negotiating without representation, it’s reasonable to ask the insurer’s adjuster to explain, in writing, exactly which benefits the settlement closes and which, if any, remain open.

Common negotiation strategies for permanent restrictions settlements
Insurers typically open with a number well below what a claim could reasonably be worth once MMI and PPD are documented, in part because early offers test whether you’ll accept quickly to avoid further delay. Treating the first offer as a starting point rather than a final number is standard practice on the worker’s side of the table.
Strengthening your position starts with documentation. A clear PPD rating, a vocational report showing how your restrictions limit suitable work, and a complete medical file supporting future care needs all give you concrete numbers to counter a lowball offer. Vague or incomplete restrictions documentation tends to produce vague, conservative offers from insurers, since they have less to work with when estimating future costs.
Timing itself is a lever. Settling before your medical treatment plan is finalized often means accepting the insurer’s estimate of future costs rather than your own, while waiting until your condition and restrictions are fully documented gives you firmer ground to negotiate from.
It also helps to separate the components of the offer rather than negotiating a single lump figure. Pushing back on the PPD award, the future medical allocation, and any wage-loss projection as distinct line items makes it easier to identify where the insurer’s number is weakest and where you have room to counter.

Finally, know your floor before you walk into a conversation. Running your own estimate through a settlement calculator ahead of time gives you a number to compare against, so you’re not evaluating the insurer’s offer in a vacuum.
Impact of permanent restrictions settlement on long-term disability benefits and employment
Settling a claim with permanent restrictions can affect both your access to future benefits and your employment path, depending on how the agreement is structured. If your settlement is full-and-final and later you need additional treatment related to the same injury, you may have no recourse through that workers’ comp claim, which makes future medical needs worth weighing carefully before you sign.
Research on lump-sum settlements shows return-to-work effects can cut in two directions: an income effect, where receiving a lump sum reduces financial pressure to return to work quickly, and a closure effect, where finalizing the claim motivates workers to move on to new employment. Which effect dominates depends on your personal circumstances, your industry, and how transferable your skills are given your restrictions.
Permanent restrictions can also intersect with separate disability programs. If you receive Social Security Disability Insurance or a private long-term disability policy, a workers’ comp settlement may trigger an offset calculation that reduces those other benefits, depending on how the settlement is structured and worded. This is a detail worth raising directly with whoever administers your other disability benefits before you finalize a workers’ comp settlement, since the interaction varies by program and isn’t always obvious from the settlement paperwork alone.
On the employment side, workers with documented permanent restrictions sometimes need formal accommodation discussions with an employer, and a settlement doesn’t erase that need. If you intend to return to your prior employer, clarifying how your restrictions will be accommodated is a separate conversation from the settlement itself, and it’s worth having before, not after, you sign.
Tax considerations related to lump-sum settlements for permanent restrictions
Workers’ compensation benefits, including lump-sum settlements for permanent restrictions, are generally not subject to federal income tax when they’re paid under a workers’ compensation act or statute for a work-related injury. This applies whether you receive the money as weekly payments or as a single lump sum, as long as the payment is genuinely a workers’ comp benefit rather than wages or a different type of settlement.
Where it gets more complicated is when a settlement overlaps with other benefits. If you’re also receiving Social Security Disability Insurance, part of your workers’ comp settlement may become taxable through the offset calculation that applies when combined benefits exceed a certain threshold tied to your prior earnings. The non-taxable status of the workers’ comp portion can shift in that specific scenario, so it’s worth a conversation with a tax professional if you’re drawing both benefits at the same time.
Settlements that include components unrelated to the physical injury, such as amounts allocated for emotional distress not tied to the physical injury or certain punitive elements, can also be treated differently for tax purposes depending on how the stipulation characterizes them. The way your settlement agreement labels each component matters more than how you personally think of the money, so precise drafting protects you here too.
Because tax treatment depends on your specific benefit mix and how your settlement is structured, this is an area where general information isn’t a substitute for checking your own situation with a tax advisor before you sign, especially if Social Security or other disability benefits are part of your picture.
Author perspective: balancing immediate needs with long-term security
Running your own numbers before you negotiate protects you from regret later. A slightly bigger check rarely outweighs losing coverage for care you’ll still need in five years. Document what you need, and talk to someone you trust when your medical future still feels uncertain.
— Daniel
Use the free calculators to estimate your settlement range
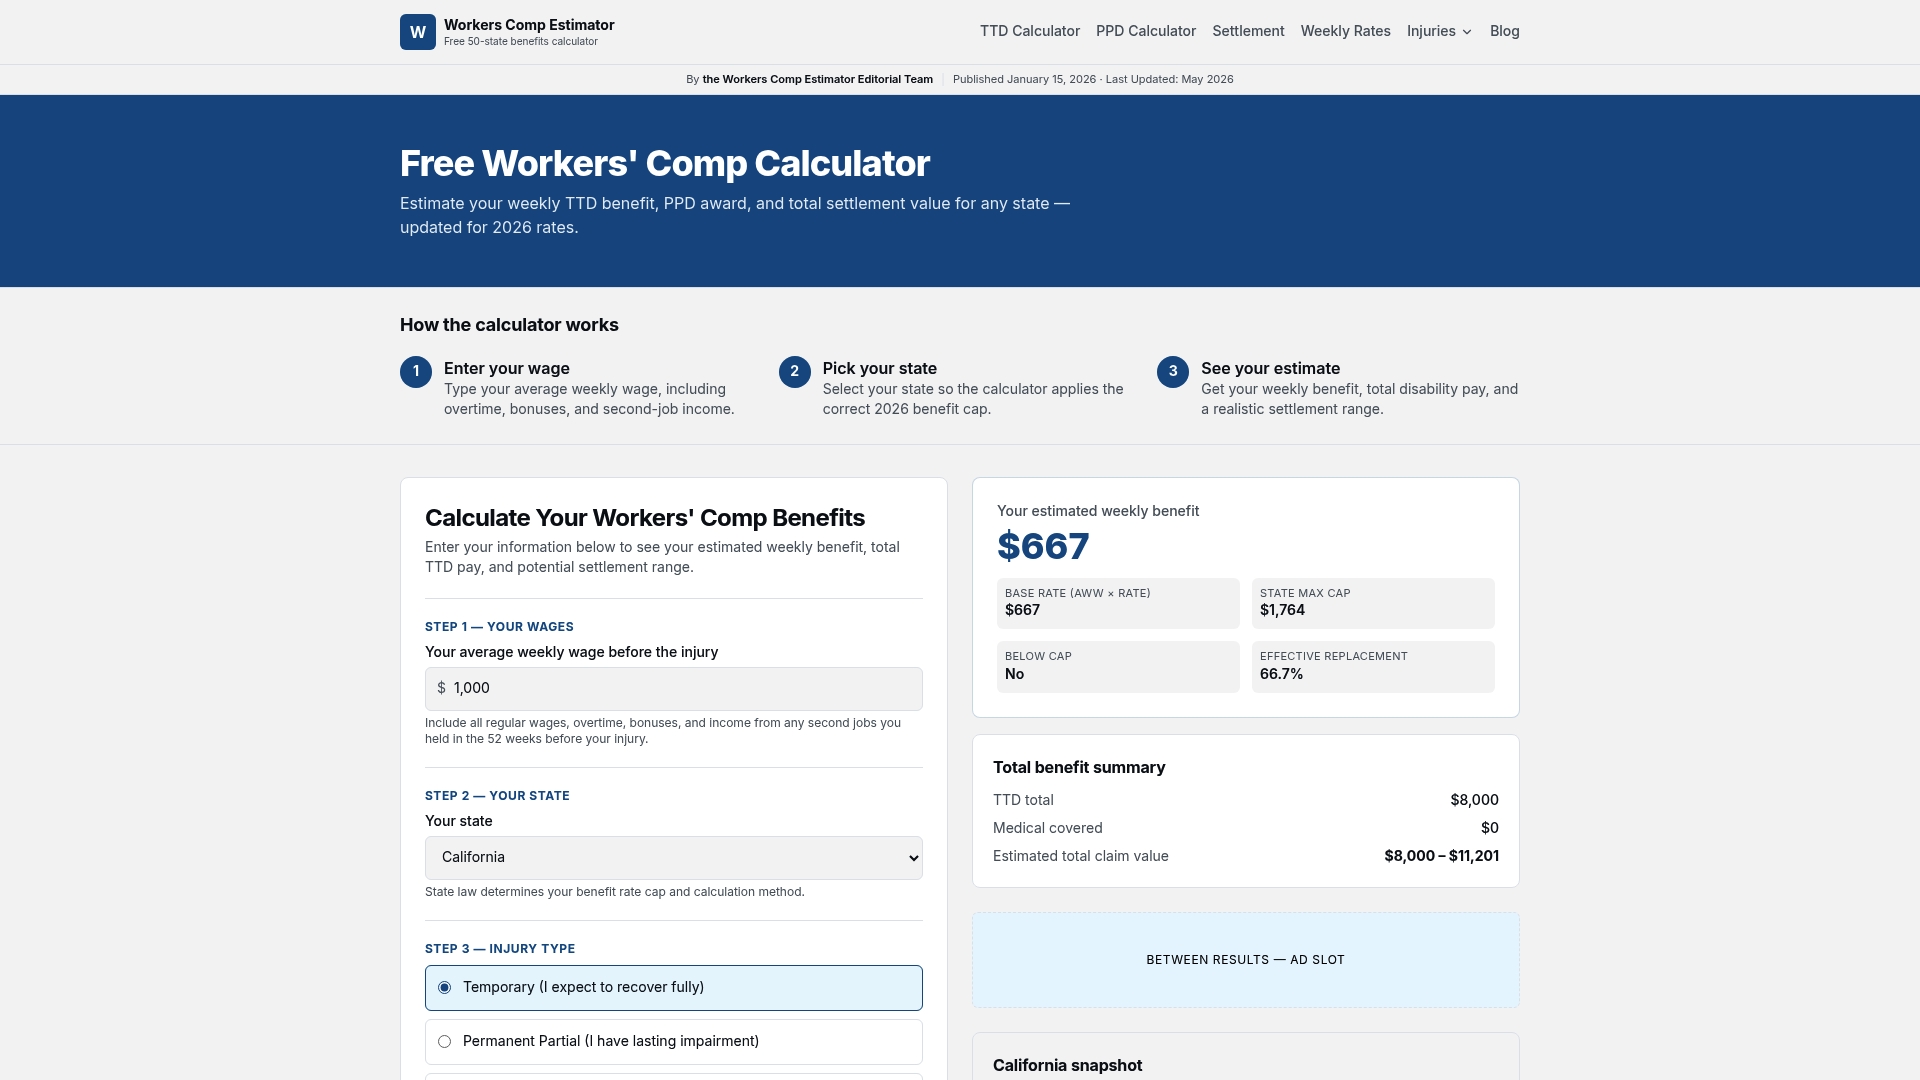
Before you sign anything, it helps to know what your claim is actually worth, not just what the adjuster says it’s worth. The Workers’ Comp Calculator uses 2026 state benefit caps and injury-specific inputs to give you a realistic starting point instead of a guess, so you walk into negotiations with your own numbers already in hand.
A few ways to put this to work right away:
- Run a PPD calculator estimate to see how your impairment rating translates into a dollar figure.
- Check a state’s weekly benefit rate to see the cap that applies to your claim.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
Does a permanent work restriction increase the settlement?
Permanent restrictions generally push settlement value higher because they signal longer-term wage loss and ongoing medical need, which insurers factor into the indemnity and future medical components. The exact increase depends on your impairment rating, your state’s formula, and whether your restrictions prevent a return to comparable work.
What is a lump-sum payment for permanent impairment?
A lump-sum payment for permanent impairment is a single payout that compensates you for a permanent loss of function, calculated from your PPD or whole-body impairment rating under your state’s formula. It can be paid alone or combined with other settlement components like future medical or wage-loss compensation, depending on how the agreement is structured.
How much will I get from a settlement?
There’s no fixed amount, since every settlement depends on your average weekly wage, impairment rating, state benefit caps, and whether future medical costs are included. Running your specific numbers through a settlement calculator gives a far more useful estimate than any flat figure, since outcomes vary significantly by state and case.
Who pays permanent partial disability benefits?
Permanent partial disability benefits are paid by the employer’s workers’ compensation insurance carrier, or by the employer directly if self-insured, once a PPD rating is issued. The payment follows the formula set by the state where the injury occurred and is typically processed as either scheduled periodic payments or a negotiated lump sum.
How does workers’ comp settlement differ from a personal injury settlement?
A workers’ comp settlement resolves a claim against your employer’s insurance for a workplace injury regardless of fault, while a personal injury settlement typically requires proving someone else’s negligence caused your harm. The two can sometimes run alongside each other if a third party contributed to your injury, but they follow different legal processes and compensation rules.
Sources
- Final Progress Report — Keys to Re-Injury Prevention and Sustained Return-to-Work for Disabled Workers (University of Washington / CDC)
- Changing settlement behavior in the New York workers’ compensation system — WCRI FlashReport
Recommended
More from the blog
Run a state specific 2026 workers' comp settlement calculation. Use the free 50 state calculator to see how state caps change your payout.
See how 2026 state caps, wages, and surgery affect your U.S. hernia workers' comp payout. Run a free 50 state calculator for a realistic estimate.
Get a state-accurate 2026 estimate for your U.S. burn injury settlement. Use the free 50-state calculator with your AWW, MMI date, impairment rating, and...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.