U.S. Workers’ Comp: Concurrent Employment Can Boost Weekly Pay by $133

Whether your second job’s wages get added into your workers’ comp benefit calculation depends on your state, but most states do include concurrent wages when you’re hurt while holding more than one job at once, and the employer where the injury happened usually pays. Before anything else, start pulling pay stubs, 1099s, and schedules from every employer you work for right now. That paper trail decides whether your benefit check reflects all your income or just one job’s worth.
TL;DR:
- States average each job separately or combine gross wages first; weeks actually worked and documented overtime, tips, or gig payouts can change the calculation.
- A $600 main job and $200 side job produce an $800 wage average and about $533 weekly at two thirds, versus $400 if excluded.
- The injury site employer usually pays, but overlapping duties, employers that insure themselves, or cross state work can trigger coverage and wage verification disputes.
- Ohio supports broad inclusion, New Mexico favors separate job averages, and Virginia may require similar duties and purposes; cross state claims need local guidance.
- Collect pay stubs, tax forms, platform payout histories, and timesheets for every job across the state’s lookback period; notify all employers promptly after injury.
Table of Contents
- How average weekly wage is calculated when you have concurrent employment
- Who pays workers’ comp benefits if you’re injured at one job but work multiple jobs
- State differences and leading court decisions to watch for
- If you’re injured while holding multiple jobs: a checklist of steps and documents to protect your claim
- Practitioner perspective: common mistakes and how to avoid them
- Get a realistic weekly benefit estimate before you talk to the insurer
- FAQ
- Sources
How average weekly wage is calculated when you have concurrent employment
Your weekly workers’ comp check is built on your average weekly wage, or AWW, and the formula your state uses determines whether your side job counts. Most statutes calculate AWW by dividing gross wages earned over a lookback period, often the 52 weeks before injury, by the number of weeks actually worked, which matters if you took unpaid weeks off or started a job partway through the year.
States generally handle concurrent jobs one of two ways:
- Separate then combine. Calculate an AWW for each employer using that job’s own hours and pay pattern, then add the two figures together.
- Aggregate then divide. Add all gross wages from every employer over the lookback period, then divide by total weeks worked to get one blended AWW.
New Mexico’s appellate guidance in Vinyard v. Palo Alto favors applying each job’s ordinary averaging method and then aggregating the results, unless unusual circumstances call for a different approach. That detail matters most for irregular or seasonal income, where “weeks actually worked” rather than calendar weeks can swing the final number significantly.
Overtime, tips, and gig payouts generally count as wages if they’re regular and documented, though insurers often push back on irregular gig income without platform payout histories to back it up.
A worked example: say you earn $600 a week at your main job and $200 a week at a part-time weekend job. Include both and your combined AWW is $800; exclude the second job and it drops to $600. At a typical two-thirds compensation rate, that’s the difference between roughly $533 and $400 a week, before any state maximum caps the payout. The Vinyard decision shows that how a state aggregates concurrent wages, not just whether it includes them, can change your weekly check by hundreds of dollars.

Who pays workers’ comp benefits if you’re injured at one job but work multiple jobs
The general rule across most states is straightforward: the employer where the injury physically occurred, and that employer’s insurer, pays the claim, even when your AWW is calculated using wages from every job you hold. The Ohio Supreme Court’s decision in the FedEx Ground Package System matter backed this approach, rejecting an employer argument to strip out concurrent wages and holding that the statute’s language supports counting all wages earned in the year before injury, not just the ones paid by the employer on the hook for the claim.
That single-payer structure sounds clean, but disputes still surface:
- Competing insurers sometimes disagree about whose policy applies when duties overlap between jobs.
- Self-insured employers may contest including outside wages they can’t easily verify.
- Cross-state work raises questions about which state’s law and wage caps govern the claim.
Insurers investigating a concurrent-employment claim will typically request pay records directly from your other employers, so it helps to notify every employer you work for once you report an injury, even the ones where nothing happened.
Pro Tip: Send a short written notice to each employer the same week you report your injury, so nobody is caught off guard when an insurer calls asking for wage verification.
State differences and leading court decisions to watch for
State law on concurrent employment is anything but uniform, and a handful of appellate decisions illustrate just how differently courts approach the same basic question. Some states aggregate wages almost automatically once concurrent employment is shown; others apply narrower tests before combining anything.
- Ohio: The Industrial Commission opinion tied to FedEx Ground supports including concurrent wages whenever the statute references wages earned in the prior year without carving out exclusions.
- New Mexico: Vinyard v. Palo Alto lays out a method of averaging each job separately before aggregating, with room for departure in unusual cases.
- Virginia: Appellate rulings apply a “substantially similar” test, combining wages from two jobs when the duties and primary purpose align closely enough, as seen in a Virginia Court of Appeals decision that combined wages from two delivery jobs with comparable duties despite different products.
Courts that reject aggregation generally worry about administrative complexity or employer fairness, but courts that favor it tend to reason that excluding concurrent wages would shortchange a worker’s real, cumulative loss of earning capacity.
If your situation involves cross-state work, a dispute between insurers, or a short-term or temporary arrangement at either job, state-specific nuance is exactly where a general rule stops being reliable. That’s the point to contact your state workers’ comp agency directly or talk to counsel, rather than assuming the rule you read about in another state applies to you.
If you’re injured while holding multiple jobs: a checklist of steps and documents to protect your claim
Protecting a concurrent-employment claim comes down to documentation and timing. Here’s the order that tends to work:
- Gather wage records first. Pull pay stubs, W-2s, 1099s, platform payout histories, and timesheets covering your state’s statutory lookback period from every employer, not just the one where you got hurt.
- Report the injury immediately to the employer where it happened, and file a formal workers’ comp claim with that employer’s insurer.
- Notify your other employers that their wage records may be relevant to the claim, even if the injury didn’t happen on their premises.
- Request that concurrent wages be included in the AWW calculation, and provide supporting payroll documentation directly rather than waiting for the insurer to ask.
- Track medical restrictions and light-duty offers carefully. Workers’ comp leave that meets FMLA’s definition of a serious health condition can run concurrently with FMLA leave, and declining a light-duty assignment you’re medically capable of performing can affect your benefits.
Pro Tip: Keep a dated folder, physical or digital, of every pay record and medical note from day one. Insurers move faster when they don’t have to chase you for documentation, and you avoid the delays that come with piecemeal evidence.
For a deeper look at how comp and leave protections interact day to day, our guide to workers’ comp and FMLA rights walks through coordination in more detail, and for readers facing retaliation or leave disputes, Serendib Law Firm’s overview of FMLA rights covers what protections look like when an employer pushes back.
Practitioner perspective: common mistakes and how to avoid them
The costliest mistake we see is silence: workers who don’t mention a second job to the insurer, assuming it’s irrelevant or none of their business. It almost never helps to leave it out, and it can look like concealment later. The second mistake is relying on memory instead of records when a state’s lookback window stretches back a full year.
Running your documented wages through a 50-state benefit calculator before insurers finalize their numbers gives you a realistic figure to measure their offer against. Keep records, ask your state agency when the rule is unclear, and bring in counsel the moment a claim gets contested.
— Daniel
Get a realistic weekly benefit estimate before you talk to the insurer
We built a free calculator specifically so you don’t have to negotiate blind. Enter wages from each employer, pick your state, and get an estimated weekly TTD benefit along with how your state’s 2026 cap might limit it, using the same aggregation logic courts in states like New Mexico and Ohio have applied to concurrent employment.
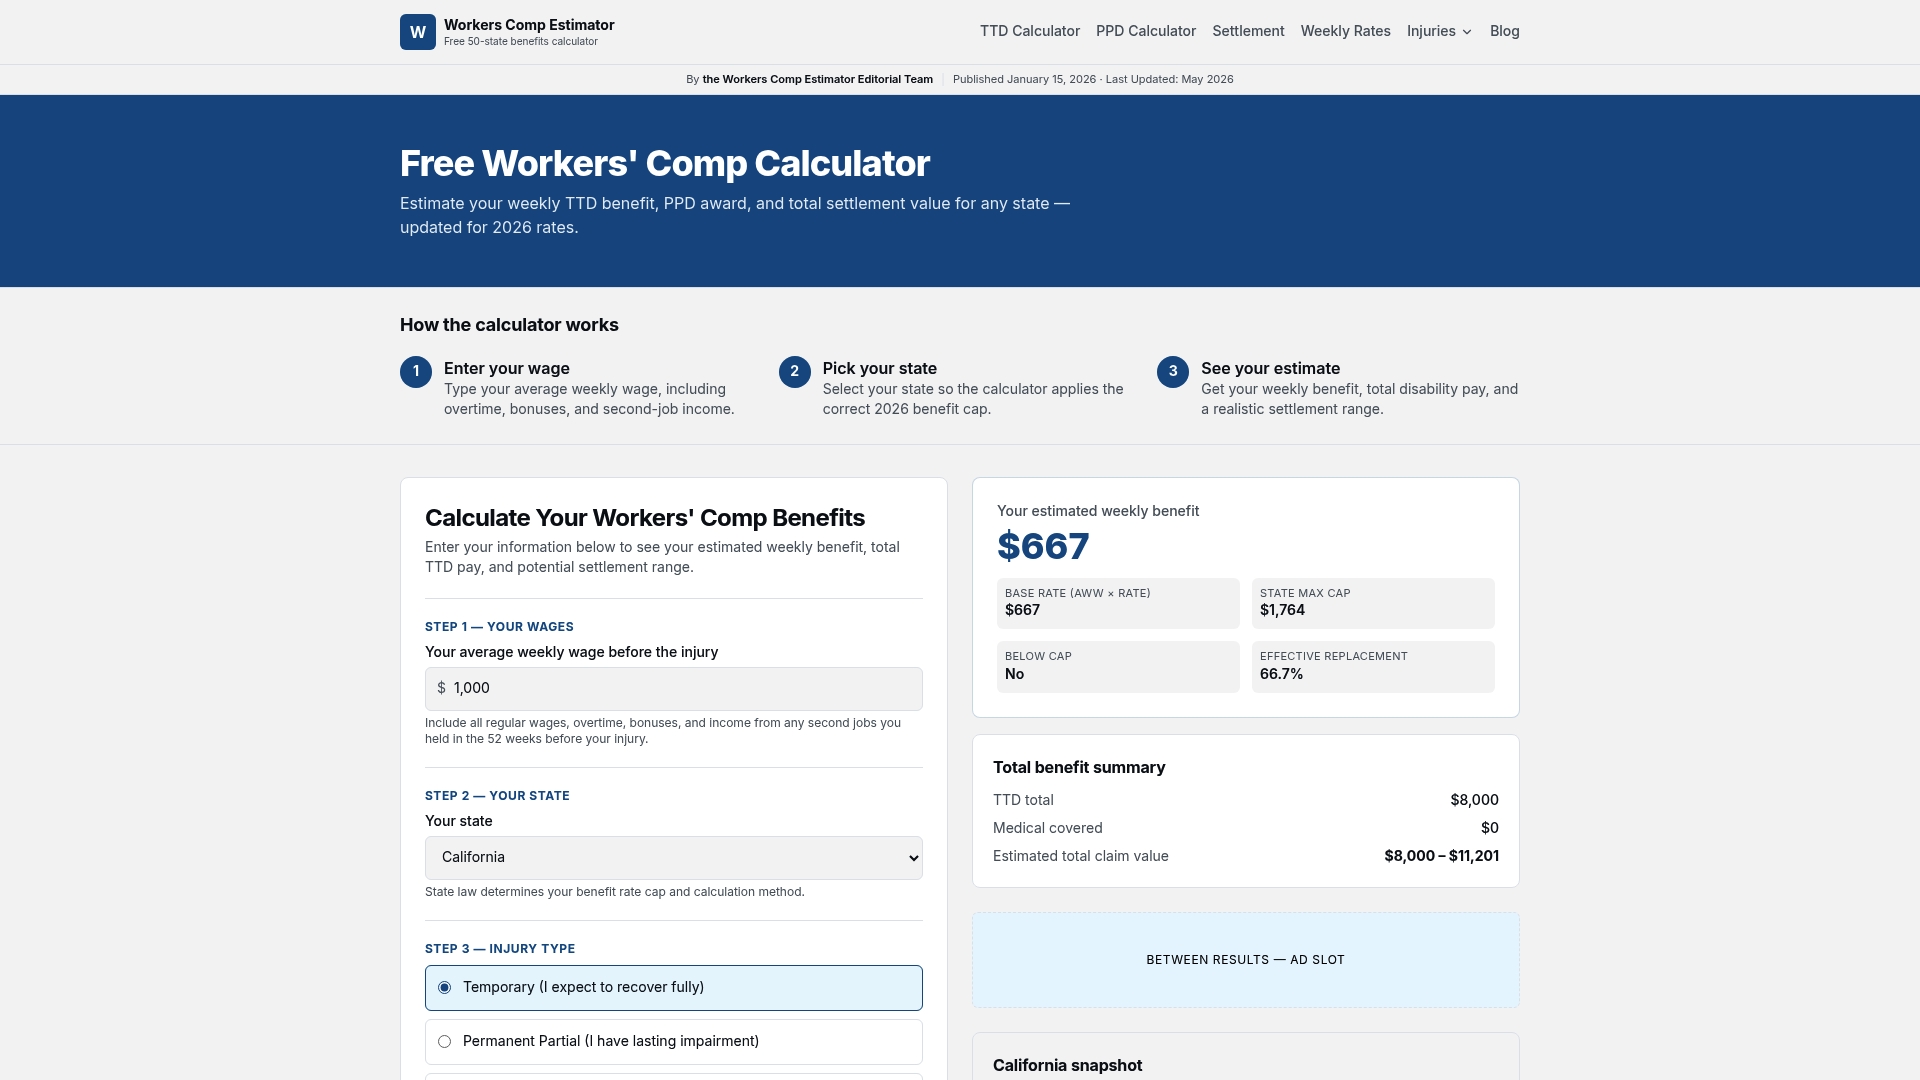
- Enter wages from every job you hold, not just the one tied to your injury.
- See how your state’s benefit cap affects the final weekly number.
- Get a grounded figure to bring into conversations with an insurer or a workers’ comp attorney.
Use it once you’ve gathered your pay records, before you accept any number an insurer hands you, so you walk into that conversation with a figure of your own. Try the free 50-state workers’ comp calculator and see where your estimate lands.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
Can I be sued for working two jobs at the same time?
Holding two jobs is not illegal and doesn’t expose you to a lawsuit on its own. Issues only arise if a specific employment contract restricts outside work or creates a direct conflict of interest, which is a matter of your individual agreement rather than a general legal rule.
Does workers’ comp run concurrently with FMLA?
Yes, workers’ comp leave and FMLA leave can run at the same time when the injury meets FMLA’s definition of a serious health condition, and employers may designate the time away as both. The Department of Labor notes FMLA provides up to 12 workweeks of unpaid, job-protected leave per year for eligible employees.
Does workers’ comp cover multiple states?
Workers’ comp coverage is generally state-specific, and whether a claim crosses state lines depends on reciprocity agreements and extraterritorial coverage rules that vary by state. If you work in more than one state, check with the relevant state workers’ comp agency, since an employer may need separate coverage where reciprocity doesn’t apply.
What’s the longest you can be on workers’ comp?
There’s no single national limit, since maximum duration for temporary disability benefits depends on your state’s statute and the nature of your injury. Benefits typically continue until you reach maximum medical improvement or hit your state’s specific time or dollar cap, whichever comes first.
Sources
- Employment Laws: Medical and Disability-Related Leave | U.S. Department of Labor
- State ex rel. FedEx Ground Package Sys., Inc. v. Industrial Commission (Ohio Supreme Court opinion excerpt)
- Vinyard v. Palo Alto (New Mexico Court of Appeals opinion)
- Court of Appeals of Virginia opinion (representative concurrence/substantial similarity example)
Recommended
More from the blog
See how 2026 state caps, wages, and surgery affect your U.S. hernia workers' comp payout. Run a free 50 state calculator for a realistic estimate.
File the correct state claim and collect medical and wage records. Run the free 50 State calculator to see your likely weekly TTD and settlement before...
Find out whether PTSD qualifies for U.S. workers' compensation, when first-responder presumptions apply, how FECA and state rules affect proof, and use a...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.