50 State Body Part Values: Calculate Your U.S. Workers’ Comp Award

Scheduled body part awards are calculated by multiplying a fixed number of weeks assigned to that body part by your state’s weekly benefit rate, subject to a statutory maximum. The weeks come from your state’s schedule of losses, the weekly rate comes from your average weekly wage (AWW) and state formula, and the cap can shrink the total for higher earners. Because every state sets its own weeks and caps, the same injury can pay very differently depending on where you work.
TL;DR:
- Most states calculate scheduled awards by multiplying fixed weeks for each body part by a fraction of the worker’s average weekly wage, subject to a maximum cap.
- The value of unscheduled injuries like back or neck issues depends on impairment ratings or wage-loss evidence rather than a fixed schedule.
- Workers with high earnings may receive the same maximum weekly benefit as lower earners due to state caps, limiting the impact of a higher paycheck.
- Reaching Maximum Medical Improvement is crucial before accepting impairment ratings, as incomplete assessments can undervalue the claim.
- Using online calculators and verifying current state schedules provides a reliable estimate to prepare for negotiations or settlement discussions.
Table of Contents
- How scheduled and unscheduled injury systems work
- Calculating your likely scheduled body part award
- State-by-state examples of body part schedules
- Using a calculator to turn the formula into a real number
- Why your job or occupation can change the value
- Partial loss versus total loss of use
- How settlements and lump sums fit into the calculation
- When schedules and caps get updated
- What injured workers get wrong about their own claims
- Get a printable estimate before you negotiate
- Sources
- FAQ
How scheduled and unscheduled injury systems work
Workers’ compensation splits permanent injuries into two broad categories, and knowing which one applies to your claim changes everything about how the value gets calculated.
A scheduled loss applies to specific body parts, most often fingers, thumbs, hands, arms, feet, legs, eyes, and hearing. States publish a table assigning a set number of weeks to each part, and total loss of that part (or a percentage of it) triggers a payout based on those weeks. According to federal research on state disability systems, about 43 jurisdictions use this kind of schedule for at least some body parts, while others rely on different methods entirely, based on a federal policy analysis of state approaches to permanent partial disability.
Unscheduled injuries cover everything not on the list, most commonly the back, neck, spine, and psychological conditions, along with cases involving whole-body impairment. These claims are valued through one of three approaches, sometimes combined:
- Impairment-based methods that convert a doctor’s percentage rating (often using the AMA Guides to the Evaluation of Permanent Impairment) into a dollar or weekly figure.
- Wage-loss methods that look at actual earning capacity lost after the injury, rather than anatomical severity alone.
- Bifurcated methods that blend impairment ratings with vocational or wage evidence to set a final number.
Schedules themselves are not uniform. Some states, like New York, express values purely in weeks per body part. Others, like New Jersey, combine weeks with dollar figures tied to the state average weekly wage. A few use percentage tables that convert directly to dollars without a weeks step at all.
Two workers with an identical amputation can still walk away with very different checks. Your AWW sets the starting point for your weekly rate, but a state maximum can cap it well below what the raw math suggests. Some states also pay more for loss of a dominant hand or add extra weeks for multiple losses on the same limb. The schedule tells you the weeks; your paycheck and your state’s cap tell you what those weeks are actually worth.
Calculating your likely scheduled body part award
The core formula behind most scheduled awards is simple: schedule weeks × weekly benefit rate = gross scheduled award. Getting an accurate number means working through three steps in order.
- Find your state’s schedule weeks and weekly maximum. Every state publishes a schedule listing weeks per body part, plus a maximum weekly compensation rate that resets periodically. New York’s Schedule Loss of Use page is a clear example: an arm is valued at 312 weeks, a hand at 244 weeks, a leg at 288 weeks, and a foot at 205 weeks.
- Calculate your weekly benefit rate. Most states pay a fraction of your AWW, commonly around two-thirds, subject to a state maximum. If your AWW is high enough that the fraction exceeds the cap, you receive the capped amount instead of the full fraction. New Jersey’s rate structure, for instance, ties the maximum to the state average weekly wage and published caps each year.
- Multiply weeks by your weekly rate. This gives the gross scheduled award before any deductions. Some states offset this figure against temporary disability benefits already paid for the same injury, so the number you calculate is a starting point, not necessarily your final check.
Before you run these numbers, gather the paperwork that makes the calculation accurate rather than guesswork:
- Recent pay stubs or a wage statement to confirm your true average weekly wage.
- Your Maximum Medical Improvement (MMI) date, since most states require MMI before issuing a permanent partial disability rating.
- A written impairment opinion from your treating or evaluating physician, stating the percentage loss of use.
Pro Tip: Run your numbers twice, once using your own AWW estimate and once using the figure listed on your wage statement or pay stubs, since even a small AWW error can shift a scheduled award by hundreds of dollars once it is multiplied across 200 or more weeks.
State-by-state examples of body part schedules
Reading an actual statute or schedule PDF is the fastest way to understand how these numbers work in practice, and the differences between states are significant.
New York lists weeks directly on its official schedule page: an arm at 312 weeks, a hand at 244 weeks, a leg at 288 weeks, a foot at 205 weeks, an eye at 160 weeks, a thumb at 75 weeks, and a first finger at 46 weeks according to the New York Workers’ Compensation Board. Say a worker with an AWW of $1,200 loses full use of a hand. New York’s weekly benefit is two-thirds of AWW, or $800 in this illustrative case, before checking it against the state’s weekly maximum. If $800 falls under the cap, the gross scheduled award would be 244 weeks multiplied by $800, or $195,200. If the cap is lower, the actual weekly figure used in the multiplication drops accordingly, which is why checking the current maximum on a New York-specific benefits calculator matters before you finalize an estimate.

Kansas takes a more granular approach in its statute, spelling out weeks for hands, arms, legs, feet, and toes, and adding specific rules for partial finger loss. Under K.S.A. schedule provisions, a partial phalange loss is treated as a fraction of the whole finger’s value rather than an all-or-nothing payout, so losing part of a fingertip pays proportionally less than losing the whole digit.
New Jersey publishes both weeks and dollar figures in its annual schedule, with the maximum weekly rate tied to the state average weekly wage. The 2026 New Jersey schedule shows how that interaction works: even a worker with a high AWW may be capped at the same maximum rate as someone earning less, which flattens the gap between high and low earners at the top end of the pay scale.
Wisconsin organizes its numbers into a detailed table rather than plain statutory text. The Wisconsin PPD schedule breaks out weeks by finger, joint, thumb, arm, hand, leg, and eye, which means two different finger joints on the same hand can carry different week values.
Not every injury fits a table like this. Back, neck, and spine injuries almost always fall outside the schedule and get valued through impairment percentages or wage-loss evidence instead, which means they typically require more medical documentation and often more time to resolve, based on the handbook analysis of PPD approaches across states.
Using a calculator to turn the formula into a real number
Working through statute weeks, wage fractions, and caps by hand is doable, but a calculator built around current state rules removes the guesswork and gives you a number you can bring straight to an adjuster.
The Free Workers’ Comp Calculator asks for a short set of inputs: your state, your average weekly wage, the injury or body part involved, an impairment percentage if you already have one from a doctor, and your MMI date if it has been reached. From there it produces a weekly TTD or PPD estimate, a schedule-based award total where applicable, and a settlement scenario that reflects your state’s 2026 benefit caps.
Once you have a result, use it as a working document, not a final answer:
- Run your state’s calculator and save or screenshot the output for your records.
- Compare that estimate line by line against any offer from the insurance adjuster.
- Bring the printed estimate to a settlement conversation as a reference point, not a guarantee.
The calculator is a planning tool, not a legal opinion. Confirm your MMI status and the exact statutory language for your body part before relying on any number, and for unscheduled injuries involving the back, neck, or a combined impairment rating, a conversation with an attorney is worth having before you sign anything.
Pro Tip: Treat the calculator’s output as your floor for negotiation, not your ceiling, since a documented impairment rating or a stronger wage record can push a real settlement above the baseline estimate.
Why your job or occupation can change the value
Job classification does not usually change the schedule weeks assigned to a body part, but it shapes the number in two indirect ways. First, your occupation determines your average weekly wage, and AWW is the single biggest driver of your weekly benefit rate once the schedule weeks are fixed. A construction worker and an office worker who both lose a thumb are entitled to the same 75 weeks under New York’s schedule, but their payouts differ because their wages differ.
Second, occupation matters heavily in unscheduled claims. A wage-loss or bifurcated valuation looks at how the injury affects your specific ability to do your job, so a hand injury that ends a career for a surgeon or a machinist carries more weight in that analysis than the same injury for someone in a desk role. Vocational evidence, including job demands and retraining prospects, becomes part of the record in these cases in a way it rarely does for a straightforward scheduled loss.

Partial loss versus total loss of use
Most scheduled injuries are not clean amputations, they are partial losses of function, and states pay a percentage of the full schedule weeks based on how much use was lost. A doctor’s impairment rating, often expressed as a percentage, is applied against the maximum weeks for that body part.
This is where the medical opinion carries real financial weight. A treating physician’s percentage and an independent medical examiner’s percentage can differ meaningfully, and that gap translates directly into dollars once it is multiplied by weeks and a weekly rate. Total loss, whether from amputation or a medical finding of complete loss of function, triggers the full schedule weeks with no percentage reduction applied.
How settlements and lump sums fit into the calculation
The weeks-times-rate formula produces a gross scheduled award, but many claims resolve through a negotiated lump-sum settlement instead of ongoing weekly payments. A settlement typically starts from that calculated figure and then adjusts for factors like disputed impairment percentages, the cost of ongoing medical treatment being closed out, and any temporary benefits already paid that offset the permanent award.
Lump sums can work in a worker’s favor when future medical costs are limited and a present-value payment beats years of smaller weekly checks, but they can also undervalue a claim when a worker accepts a number without confirming it against the statutory formula first. Comparing a settlement offer against your own weeks-times-rate calculation, done before negotiations start, gives you a concrete baseline rather than relying on the adjuster’s framing of what is fair.
When schedules and caps get updated
State schedules and weekly maximum rates are not fixed permanently. Many states adjust their maximum weekly compensation rate on a recurring basis, often tied to the state average weekly wage, which means the cap that applies to your claim depends on your date of injury, not the date you file or settle. New Jersey’s schedule and rate chart, for example, is published as a dated annual document that changes from year to year. Ohio publishes a multi-year compensation rate chart showing how its rates have shifted across categories over time.
Schedule weeks themselves change far less often than dollar caps, but they are not permanently frozen either, and legislative amendments do occur. Always check the current version of your state’s schedule and rate table rather than relying on a number you saw in an older claim or a friend’s settlement, since the effective date attached to your specific injury date controls which numbers apply.
What injured workers get wrong about their own claims
The biggest mistake I see is workers accepting an early settlement offer before reaching MMI, when the eventual impairment rating is still unknown and the offer is essentially a guess dressed up as a number. Wait for MMI, get the rating in writing, and pull your own pay stubs to confirm your AWW before you compare any offer against your own calculation.
A second medical opinion is worth pursuing when your treating physician’s impairment percentage seems low relative to your actual limitations, since that percentage is multiplied directly into your award. Keep every document: screenshots of calculator results, the specific statute page for your state, and your own AWW math. That paper trail is what turns a negotiation from a guessing match into a documented disagreement over specific numbers.
— Daniel
Get a printable estimate before you negotiate
You already have the formula: weeks times your weekly rate, capped by your state’s maximum. The Free Workers’ Comp Calculator turns that formula into a specific number for your state, your wage, and your injury, using each state’s 2026 benefit caps so the figure reflects current law rather than an outdated table someone forwarded you.
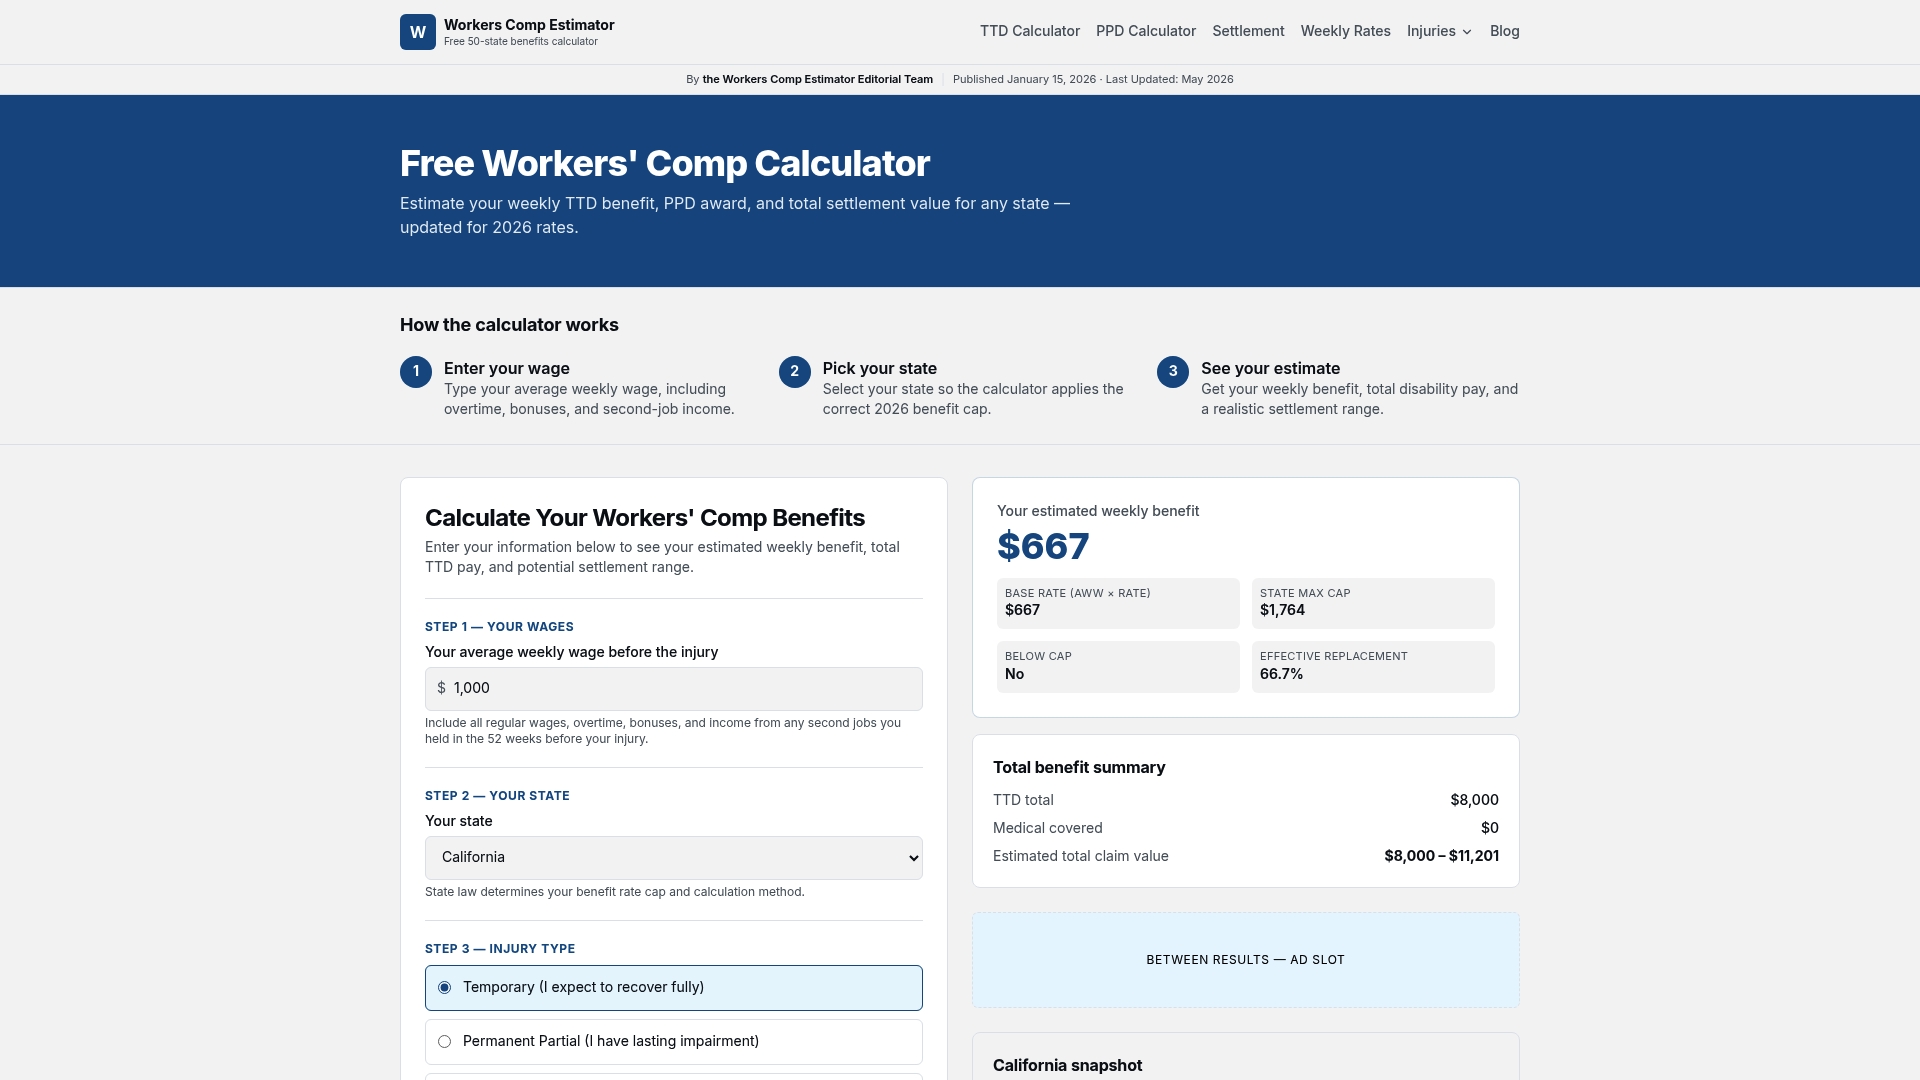
- Start with the main calculator to get a baseline weekly and scheduled award estimate for your state.
- Check the PPD Calculator if your injury involves an impairment percentage rather than a clean schedule entry.
- Compare a lump-sum offer against ongoing weekly totals using the settlement calculator before you sign anything.
Save or screenshot your results before any call with an adjuster. If your claim involves a disputed impairment rating or an unscheduled injury like a back or neck condition, the practice-area resources at Optimum Employment Lawyers walk through how medical testimony and impairment percentages get weighed in more complex cases. Run your numbers now at Workerscompestimator.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Schedule Loss of Use Award — New York Workers’ Compensation Board
- Compensating Workers for Permanent Partial Disabilities — Social Security Administration
- New Jersey schedule (2026) — State PDF
- Wisconsin PPD schedule — DWD
- Kansas statute — Compensation for certain permanent partial disabilities; computation thereof; schedule
FAQ
How are body part values calculated in workers’ comp?
Most states multiply a fixed number of schedule weeks for that body part by your weekly benefit rate, which is a fraction of your average weekly wage subject to a state maximum. New York, for example, lists an arm at 312 weeks and a hand at 244 weeks on its official schedule.
What is the difference between scheduled and unscheduled injuries?
Scheduled injuries involve body parts listed on a state’s official table, such as fingers, hands, arms, and feet, with a set number of weeks assigned to each. Unscheduled injuries, like back or neck conditions, are valued through impairment percentages or wage-loss evidence instead, based on a federal analysis of state PPD systems.
Does a higher paycheck always mean a bigger settlement?
Not necessarily, because most states cap the weekly benefit rate at a maximum regardless of how high your actual wage is. A worker earning well above the cap and a worker earning right at the cap can receive the same capped weekly amount once that maximum is reached.
How does MMI affect my body part value?
Maximum Medical Improvement is the point at which your condition is considered stable, and most states require it before issuing a permanent impairment rating tied to your scheduled award. Settling or accepting a percentage before reaching MMI risks locking in a number based on an incomplete medical picture.
Can I estimate my own award before talking to an adjuster?
Yes, using your state’s schedule weeks, your average weekly wage, and your state’s current maximum weekly rate, or by running those same inputs through the Free Workers’ Comp Calculator, which applies 2026 state caps to produce a scheduled award or settlement estimate you can bring into negotiations.
Recommended
More from the blog
See how 2026 state caps, wages, and surgery affect your U.S. hernia workers' comp payout. Run a free 50 state calculator for a realistic estimate.
Use the free 50-state estimator that applies 2026 state caps to estimate your workers' comp lump sum. Run your numbers, check SSDI/Medicare impact, and...
Use 2026 U.S. state caps and a free 50‑state calculator to estimate your permanent disability workers' comp pay. Learn P&S/MMI ratings, apportionment, and...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.