U.S. Workers: File a Second Injury Fund Claim in 4 Steps

A Second Injury Fund can pay you if you already had a documented permanent impairment and a new work injury made your overall disability worse, but only in states that still operate one. These state funds cover the extra disability caused by combining an old injury with a new compensable one, so your employer’s insurer is not stuck paying for damage it did not cause. Rules, benefits, and even the fund’s existence vary by state, so check your state’s labor or insurance department before assuming you qualify.
TL;DR:
- Not all states still operate Second Injury Funds, and those that do vary significantly in how much they pay and who is eligible to file.
- Filing requires documented proof of a prior permanent impairment, a new compensable injury, and evidence that their combination increased overall disability beyond the original injury.
- The employer or insurance carrier must typically cover the new injury’s disability first, with the fund paying only for the excess caused by the combination.
- Fund payments often depend on release of the primary claim’s final award or settlement, and the process can involve lengthy administrative hearings.
- Employers fund these programs through loss-based assessments, which influence workers’ insurance premiums and may lead to fund reductions or closures over time.
Table of Contents
- What a second injury fund is and how it works
- Which states still operate SIFs and how they differ
- Eligibility, evidence, and the application process
- How SIFs interact with employer and carrier liability
- How SIFs are funded and what that means for employers
- Practical checklist: documents, deadlines, and when to get help
- Common pitfalls and realistic expectations
- How a benefits calculator helps you plan around a SIF claim
- Primary state pages and authoritative analyses to consult next
- FAQ
What a second injury fund is and how it works
State agency pages describe the Second Injury Fund as a program that pays the excess disability created when a compensable workplace injury combines with a prior permanent impairment. The idea began decades ago as a hiring incentive: employers worried that hiring a worker with a missing eye, a fused joint, or an amputation meant taking on full liability if a second injury made that worker permanently and totally disabled. Second Injury Funds spread the risk so employers would not discriminate against applicants with disabilities.
The mechanics follow a set order. Your employer’s insurance carrier pays for the disability caused by the new injury alone, using standard workers’ compensation rules. The fund steps in only for the portion of disability attributable to combining the old impairment with the new one.
- The employer or carrier is responsible for the new injury’s own disability rating.
- The fund covers the excess disability that results from combining it with a documented prior condition.
- Common statutory tests include prior loss of use of a body part, combined disability ratings, or a finding of permanent total disability.
Which states still operate SIFs and how they differ
Not every state has an active Second Injury Fund, and the ones that remain differ widely in what they pay and who can file. Missouri still runs an active fund through the Missouri Department of Labor, and Connecticut maintains a fund overview on its state portal, though Connecticut closed the fund to most new claims after a statutory cutoff date, meaning current claims there are largely legacy cases. Texas operates a Subsequent Injury Fund through the Texas Department of Insurance that can pay lifetime income benefits or reimburse carriers depending on how the claim is structured. Indiana’s fund, summarized in ICRB references, ties eligibility to a prior total loss or loss of use of a body part combined with a later compensable injury. New Hampshire has also limited its fund’s scope over time.
- Some states closed their funds to new claims decades ago, leaving only legacy liabilities.
- Active funds differ in whether they pay ongoing lifetime benefits or a one-time reimbursement to the carrier.
- Always confirm current rules on your own state’s labor or insurance department page before filing.
Eligibility, evidence, and the application process
Qualifying for a Second Injury Fund claim generally requires three things: a documented prior permanent impairment, a new injury that is compensable under your state’s workers’ compensation law, and proof that the two combined to increase your overall disability beyond what the new injury alone would cause. State summaries, including Indiana’s, describe this as a prior total loss or loss of use of a body part paired with a second qualifying injury.
The evidence that matters most includes prior medical records documenting the original impairment, any prior workers’ comp awards or settlements tied to it, independent medical examinations addressing the combined effect, and employer or carrier records showing you disclosed the condition where required.
- File your workers’ compensation claim for the new injury through the normal process.
- Reach a final award, settlement, or exhaustion of the employer’s liability on that claim.
- Submit your Second Injury Fund application, including all supporting medical and award documents.
- Expect a possible administrative hearing before the fund’s custodian, which can add months to the timeline.
Pro Tip: Request certified copies of every prior award or settlement the day you receive them, since fund custodians often reject claims for missing documentation years later.
How SIFs interact with employer and carrier liability
Payment order matters more than most claimants expect. The employer or carrier pays first, covering the disability the new injury caused on its own. Practically, state pages and practice notes advise treating SIF claims as contingent on that primary disposition, because fund payments are often triggered only after the employer’s obligation is satisfied.
- Texas’s fund description shows it may pay lifetime income benefits or reimburse the carrier, depending on how state law frames the claim.
- Preserve every final award and settlement document, since these are frequently the primary proof needed to trigger fund payment.
- Disputes commonly arise when a carrier tries to shift more liability onto the fund than the law allows.
- Settlement language that fails to separate the new injury’s disability from the combined disability can create problems when you later file with the fund.
How SIFs are funded and what that means for employers
Second Injury Funds do not appear out of nowhere. An actuary issue brief explains that loss-based assessments fund SIF liabilities in a number of states, with assessment rates that vary widely by state and change over time. Insurers pay into the fund based on their loss experience, and those costs typically get folded into premium loadings that employers eventually absorb.

The mechanics matter for employers and claimants alike: loss-based assessments create premium loadings that indirectly affect what employers pay for coverage, which is part of why some states have scaled back or closed their funds rather than let assessments grow unchecked.
NCCI ratemaking resources explain how loss costs, assessments, and administrative charges get incorporated into state rating filings, which is the mechanism that eventually shows up in your employer’s premium. For an injured worker, this history mostly explains why some states still pay generous fund benefits while others have wound theirs down or reimburse carriers instead of paying claimants directly.
Practical checklist: documents, deadlines, and when to get help
Preparing early makes the difference between a smooth Second Injury Fund claim and a rejected one. Start collecting documentation the moment you suspect a prior condition might be relevant to your case.
- Gather prior medical records, prior workers’ comp awards or settlements, and any independent medical exam reports tied to the earlier condition.
- Keep copies of employer correspondence, especially anything showing you disclosed the prior impairment.
- File your Second Injury Fund application only after your primary claim reaches a final award or settlement, and track your state’s filing deadline closely.
- Talk to a workers’ compensation attorney if the fund custodian disputes your claim, if liability between the carrier and fund is unclear, or if a hearing gets scheduled.
Pro Tip: Run your numbers through a 50-state benefits estimator before any settlement talks, so you know your state’s weekly benefit cap and can spot a lowball offer immediately.
Common pitfalls and realistic expectations

The biggest mistake claimants make is assuming the fund pays quickly or automatically once eligibility looks obvious on paper. It does not. Second Injury Fund claims are administrative processes, often slower than the underlying workers’ compensation case, and custodians scrutinize prior-impairment evidence closely.
A second common error is misunderstanding who pays first: workers sometimes delay filing with the fund because they expect it to intervene before the employer’s carrier has finished its obligation, which only wastes time. Document everything from the earlier injury the day you realize it might matter later, and plan settlements conservatively rather than assuming fund money will arrive on a predictable schedule.
— Daniel
How a benefits calculator helps you plan around a SIF claim
Figuring out what a Second Injury Fund claim might be worth starts with knowing your basic workers’ compensation numbers first. The Workers’ Comp Calculator’s free 50-state estimator uses each state’s benefit caps to give you a realistic weekly TTD figure and a settlement range before you sit down with an adjuster or a fund custodian.
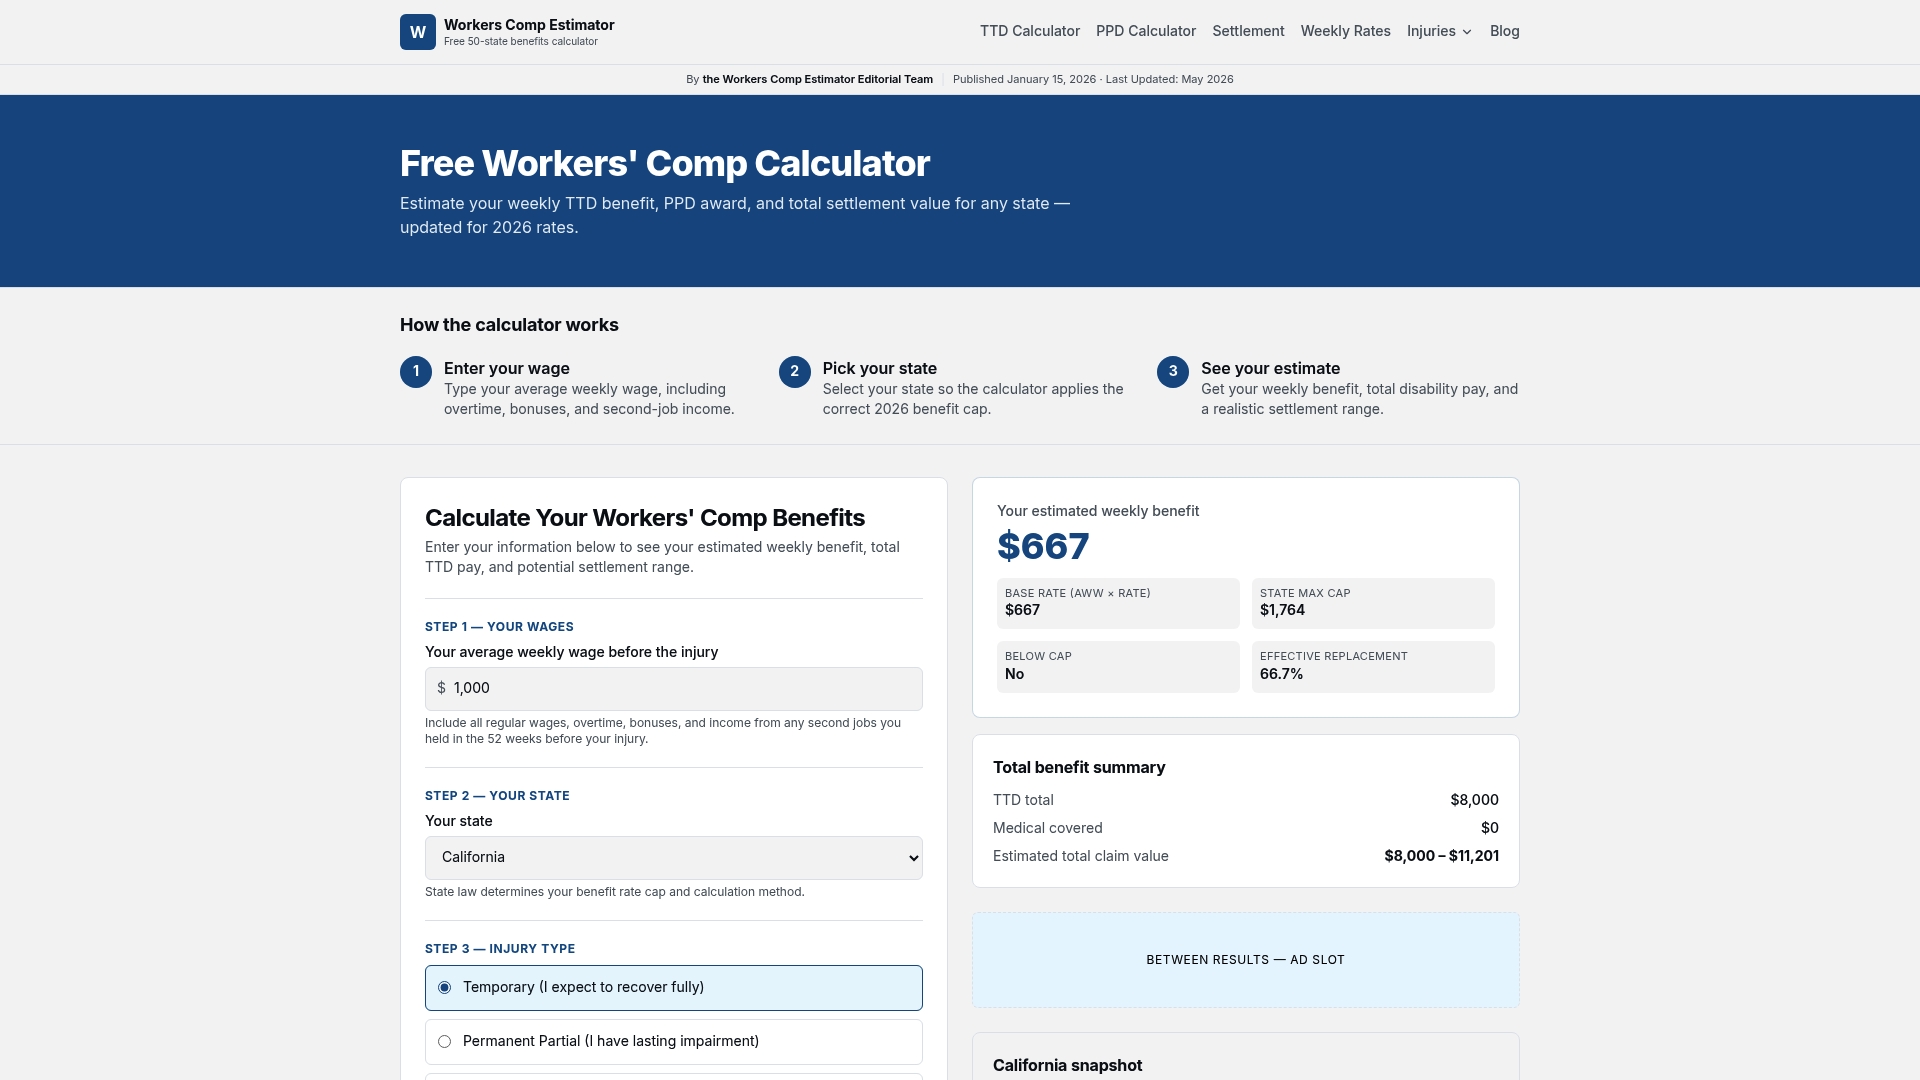
If your prior impairment involved a specific body part, injury-specific tools like the shoulder injury calculator or the back injury calculator can sharpen that estimate further, and the PPD calculator helps when combining an old permanent impairment rating with a new one. Run your numbers at Workerscompestimator before you negotiate anything.
Primary state pages and authoritative analyses to consult next
Confirm your state’s exact rules directly: the Missouri Department of Labor and the Texas Department of Insurance’s Subsequent Injury Fund page cover statute language, deadlines, and application forms you will need. If a personal injury claim might also apply to your situation, this comparison of workers’ comp and personal injury recovery explains how the two interact.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What does the second injury fund pay?
A Second Injury Fund typically pays the extra disability that results when a documented prior permanent impairment combines with a new compensable injury, rather than the full cost of either injury alone. Depending on the state, this can mean lifetime income benefits, as Texas’s fund description outlines, or a reimbursement paid to the carrier instead of directly to the worker.
Do all states have subsequent injury funds?
No. Some states, including Connecticut, have closed their funds to most new claims after a statutory cutoff date, leaving mostly legacy cases still active. Others, like Missouri, Texas, and Indiana, continue to accept new claims under their own eligibility rules, so you need to check your specific state’s labor or insurance department page.
How does the second injury fund work in Missouri?
Missouri’s fund, administered through the Missouri Department of Labor, pays benefits when a documented prior permanent impairment combines with a new work injury to increase the worker’s overall disability. Claimants generally need to reach a final resolution on the new injury claim before pursuing the fund portion, and the process can include an administrative hearing.
What is the maximum weekly compensation rate in South Carolina for 2026?
This figure is not publicly listed in the sources used for this article. Check South Carolina’s Workers’ Compensation Commission directly, or use a state-specific benefits calculator to estimate your weekly rate based on your own wage.
What evidence do I need to file a second injury fund claim?
You generally need medical records documenting your prior permanent impairment, any earlier workers’ comp awards or settlements, independent medical exam findings addressing the combined disability, and records showing when you disclosed the condition to your employer. Preserving your final award or settlement from the new injury is essential, since fund payment is usually contingent on that primary disposition being resolved first.
Recommended
More from the blog
File the correct state claim and collect medical and wage records. Run the free 50 State calculator to see your likely weekly TTD and settlement before...
Compare workers' comp and disability for U.S. workers: what each pays, SSDI's five-month wait, tax rules, and a free 50-state calculator to estimate your...
Find out whether PTSD qualifies for U.S. workers' compensation, when first-responder presumptions apply, how FECA and state rules affect proof, and use a...
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.