U.S. Workers’ Comp Settlement Timeline: MMI First, Payment Later

Most workers’ comp settlements take varying amounts of time, depending on the case and state. Simple, agreed cases may resolve sooner than disputed ones, and settlement talks often depend on medical recovery and when the parties can agree on terms. The main driver is maximum medical improvement (MMI), the point where your condition has stabilized. After that, state review and any waiting period decide when the case is actually final.
TL;DR:
- Settlement value often depends on your impairment rating at MMI, combined with wages and the state benefit schedule; settling earlier can miss later problems.
- To limit avoidable delays, keep forms and medical records complete, answer insurer requests promptly, and ask for written reasons for any dispute.
- A signature may not finalize a settlement, because states may require approval; Washington allows 30 days to revoke settlements initiated by its agency.
- Payment deadlines begin at different legal milestones; Minnesota generally allows 14 days after filing, while Arizona sets 15 days after approval, so document dates.
Table of Contents
- How long does a workers’ comp settlement usually take?
- Why does MMI usually control when a settlement happens?
- What factors delay a settlement offer?
- How do state approval and waiting periods affect finality?
- When should settlement money arrive, and what if it’s late?
- When should you keep negotiating, and how do lawyers affect timing?
- What should you gather to avoid delays?
- Why honest timing expectations protect you
- Where can you estimate your settlement before negotiating?
- FAQ
- Sources
- Where can you confirm your state’s exact deadlines?
How long does a workers’ comp settlement usually take?
There is no universal clock. Settlement timing varies by state and case complexity, and it is consistently tied to the worker reaching MMI. That is why “average” numbers can mislead: they blend easy cases with fights that drag on for years.
A realistic way to picture it is by broad categories:
- Shorter: minor injuries, no disputes, a quick return to work.
- Middle: cases where settlement discussions begin once treatment winds down.
- Longer: disputed, complex or litigated claims, especially those involving hearings.
Delay carries real stakes. A population-level study of claims data found that longer claim-processing times were associated with longer work disability durations. Slow processing is more than an inconvenience. It can stretch the whole recovery period. For a plain-language companion read, see our article on when workers’ comp will offer a settlement.
Why does MMI usually control when a settlement happens?
MMI means your doctor has concluded your condition is unlikely to improve much more with treatment. Settlement discussions are often tied to MMI, since the worker’s condition and any impairment rating can affect the terms.
There are two flavors. Clinical MMI is a medical judgment about your recovery. Statutory MMI is a date set by law. Some state guidance uses a 104-week rule, for example, and requires that impairment ratings reflect your condition on the MMI date.
That rating matters because it feeds the settlement math. Your impairment rating at MMI, combined with your wage and your state’s benefit schedule, shapes the lump-sum value. You can see how body-part schedules affect payouts in our settlement chart by body part. If you need quick definitions of terms like TTD, PPD and MMI, our guide to how workers’ comp works covers them.

What factors delay a settlement offer?
Most delays come from three places, and you can influence some of them.
Medical complexity. Conditions that are slow to stabilize, such as neurological injuries or mental-health conditions, tend to lengthen timelines because MMI arrives later.
Disputes. Disagreements over the extent of the injury, future medical needs or whether the claim is compensable can require hearings and delay agreement.
Administrative friction. Missing forms, adjuster turnover and payments routed through several offices can cause delays. These issues do not necessarily reflect on the strength of your claim.
The practical takeaway: you cannot speed up healing, but you can keep paperwork complete, respond to requests quickly and ask for written reasons whenever something is disputed. Those small habits keep an administrative problem from becoming a months-long stall.
How do state approval and waiting periods affect finality?
Settlements are voluntary agreements, but they usually do not take effect on signature alone. Many states require a judge or agency to review the deal to confirm it is adequate. That review protects you, and it also adds time.
Some states then add a revocation or cooling-off window during which a party can change its mind. Washington’s claim resolution process is one example of a system with a mandatory revocation period, and agency-initiated settlements there use a 30-day revocation period. Until that window closes, the settlement is not truly final.
The important wrinkle is that the “start date” for each clock differs by state. One state counts from approval, another from filing, another from the end of a waiting period. Before you plan around a date, confirm your own state agency’s process rather than assuming a neighboring state’s rules apply.
When should settlement money arrive, and what if it’s late?
After approval and any waiting period, payment is usually due within a short, set window. Statutes vary. Minnesota generally requires payment within 14 days of the award being filed, while Arizona’s statute sets a 15-day timeframe after an administrative law judge approves a full and final settlement. Some states also add penalties for payments that are late without a good reason.

How the deadline is calculated can turn on appeal windows and statutory wording. North Carolina case law shows why you need to know exactly when payment becomes due before penalties attach.
If a payment slips, documentation is your leverage. Keep the award or approval date, the approval letter and every piece of correspondence with the insurer. A dated paper trail makes a late-payment complaint much easier to support.
When should you keep negotiating, and how do lawyers affect timing?
Know which kind of settlement is on the table. In California, for example, you can settle by stipulation or by compromise and release. A stipulation pays agreed disability amounts over time, while compromise and release is a single lump sum. A full settlement typically closes the file and can end the insurer’s duty to pay for future medical care unless that care is specifically included.
An attorney may help you assess an offer and negotiate, but representation can lengthen the timeline if valuation or hearings take time. That tradeoff is often worth it when the injury is serious or the offer looks thin.
Before accepting, run through three checkpoints:
- Your medical condition is stable.
- Future medical coverage is included, or you have deliberately weighed giving it up.
- You have a clear impairment rating you trust.
If any of the three is missing, keep negotiating.
What should you gather to avoid delays?
A prepared file moves faster and makes any offer easier to judge.
- Medical records, MMI reports and impairment ratings
- Wage statements and the employer’s incident report
- Every letter, email and note from the insurer
- A dated log of treatment, work status and calls with claims staff
- Written reasons for any denial or dispute
- A second medical opinion if your impairment rating looks low
Pro Tip: Before any negotiation call, plug your wage and rating into a settlement calculator so you already know a reasonable range and can spot a lowball offer.
Why honest timing expectations protect you
I’ve spent my time building state-specific calculators, and the pattern is consistent: people who expect a quick payout are the ones most tempted to accept a rushed, low offer. Realistic timing gives you room to wait for MMI and a fair rating. Rules differ widely, so verify your state’s process and talk to counsel when you are unsure.
— Daniel
Where can you estimate your settlement before negotiating?
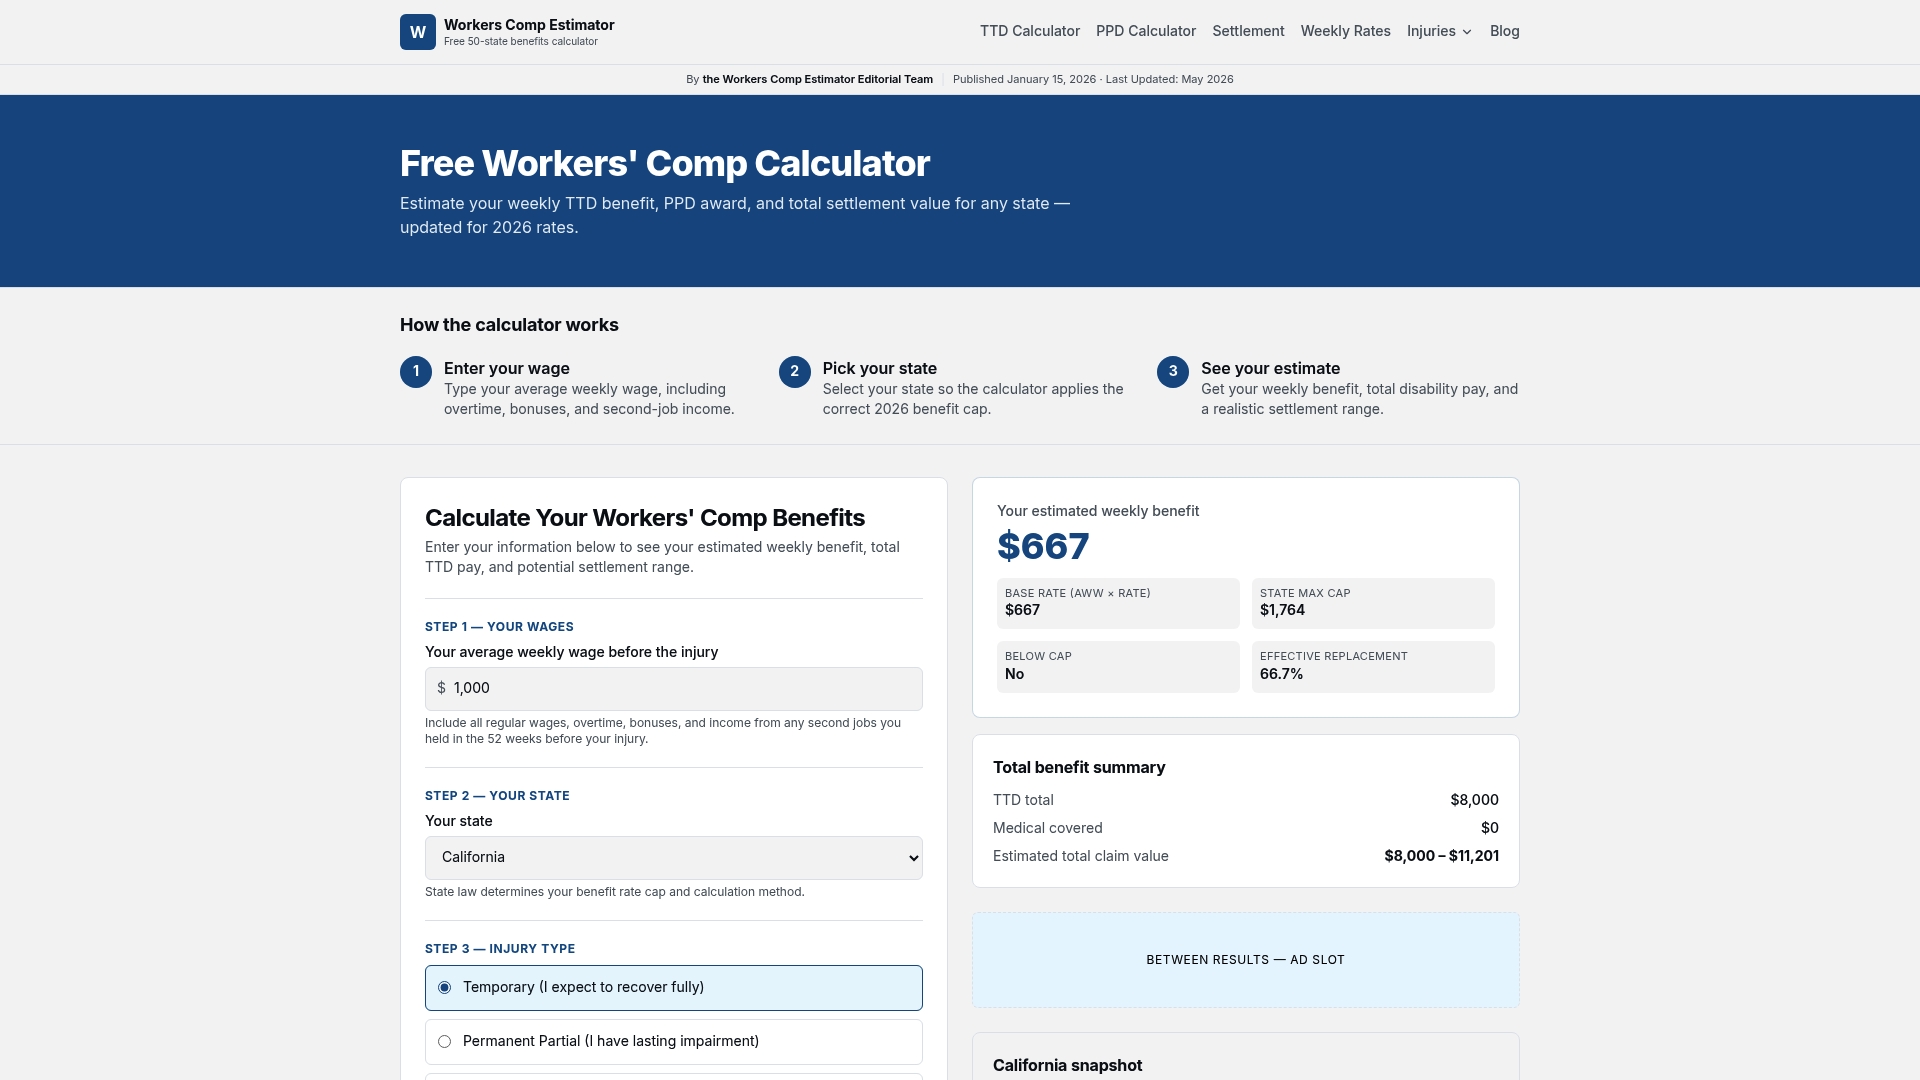
Walking into negotiations with a number in mind changes the conversation. Our free calculators use state benefit caps, so the estimates reflect what your state allows:
- Weekly TTD estimates from your wage and state
- Settlement scenarios in our settlement calculator
- Impairment payout estimates for your rating
- State rules and caps through our state estimator
We built these so you can check an offer against realistic ranges before you respond. Run your numbers today and take them into your next call with the adjuster.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
How long does a workers’ comp settlement take to get paid?
Once a settlement is approved and any waiting period ends, payment typically follows within a few weeks. Exact deadlines are set by state law, such as 14 days in Minnesota after an award is filed.
Can I get a workers’ comp settlement before reaching MMI?
It is possible in some cases, but settlements are generally tied to MMI because your long-term condition must be known to value the claim fairly. Settling early risks giving up compensation for problems that appear later.
Do I have to pay back workers’ comp when I settle?
Generally, settlement money is for your benefit, but liens or reimbursement claims can apply depending on state law and who paid your medical bills. Ask your agency or an attorney how liens work in your state before you sign.
Does hiring an attorney make my settlement take longer?
Sometimes, since a full valuation and possible hearings add time. The extra time often goes toward a stronger offer, especially for serious or disputed injuries.
Sources
- Guide to indemnity dispute settlement
- Settle a Claim (Claim Resolution Settlement Agreements)
- Settling a Case | Missouri Department of Labor and Industrial Relations
- Sec. 176.521 MN Statutes
Where can you confirm your state’s exact deadlines?
Check your state’s labor or workers’ compensation agency and its statutes for the official forms and payment clocks.
Recommended
More from the blog
Understand U.S. workers comp waiting periods (typically 3–7 days). See state examples, learn how to protect and claim retro pay, and use a free 50 state...
Find out whether PTSD qualifies for U.S. workers' compensation, when first-responder presumptions apply, how FECA and state rules affect proof, and use a...
Run a state specific 2026 workers' comp settlement calculation. Use the free 50 state calculator to see how state caps change your payout.
Free workers' comp calculators
Put the numbers in this article to work on your own claim.
Weekly benefit, PPD, and settlement in one place.
What your weekly temporary disability check should be.
Scheduled weeks and permanent impairment awards.
Light-duty benefit when you earn less while healing.
Federal employee FECA award by body part.
Lump-sum value of your full claim.
Turn a 5%, 10%, or 20% rating into dollars.
Max and min weekly rates for all 50 states.
Typical settlement ranges by injury and state.
Average settlement for fusion, rotator cuff, knee replacement, and more.
Why comp does not pay it, and when a third-party claim does.
When carriers typically make an offer.
What coverage costs by class code and payroll.
Guides, state updates, and claim strategy.